
Indonesia
Policies & action
The CAT rates Indonesia’s policies and actions “Highly insufficient” when compared to their fair share contribution to climate change mitigation.
The “Highly Insufficient” rating indicates that Indonesia’s climate policies and action are not consistent with the Paris Agreement’s 1.5°C temperature limit and lead to rising, rather than falling, emissions. If all countries were to follow Indonesia’s approach, warming could reach over 3°C and up to 4°C.
According to the CAT's latest policy projections, Indonesia’s emissions are set to increase between 1,494–1,509 MtCO₂e by 2030 (excl. LULUCF), or 51%–53% above 2019 levels. This range is lower than our previous assessment because the latest national inventory-based historical emissions series revised recent emissions downwards, creating a lower starting point for the projections rather than reflecting stronger policy implementation. Even with this downward correction, projected emissions remains far above levels compatible with a 1.5°C fair share pathway, which would require emissions to be reduced to at least below 927 MtCO₂e by 2030, or 6% below 2019 levels.
Further information on how the CAT rates countries (against modelled domestic pathways and fair share) can be found here.
Policy overview
Since taking office in October 2024, the Prabowo-Gibran administration has maintained headline commitments such as net zero by 2060, while pursuing an ambitious 8% economic growth target through downstream industrialisation and self-sufficiency in food and energy. These priorities often rely on fossil fuels and large-scale agricultural projects, raising concerns that economic objectives are taking precedence over environmental integrity.
Indonesia’s 2025 National Energy Policy (KEN) reflects this mixed direction. It sets the primary energy mix targets at 19–23% new and renewable energy by 2030, 36–40% by 2040, 45–53% by 2050, and 70–72% by 2060, but still leaves coal at around 40% in 2030, 20% in 2050, and 10% in 2060, while fossil gas is expected to account for 14% in 2030, rising to 17% in 2050 and 15% in 2060. The policy also highlights bioenergy (biomass, biogas, and biofuels) as key components of the future energy mix, while promoting high-risk technologies such as nuclear power and unproven carbon capture, utilisation and storage (CCUS).
JETP implementation has not yet become a decisive driver of Indonesia’s power sector transition. The upcoming Comprehensive Investment and Policy Plan (CIPP) update broadens the agenda to captive coal decarbonisation, energy efficiency, electrification, carbon pricing and just transition, but early coal retirement appears to have been deprioritised, and the cancellation of the early pilot retirement of the flagship Cirebon-1 coal plant further weakens the initiative’s credibility.
The power sector is still dominated by fossil fuels. The new RUPTL 2025–2034 backloads most renewable additions until after 2030 while expanding coal and fossil gas capacity in the next four years, raising risks of oversupply, stranded assets, and long-term lock-in. The announced 100 GW solar and battery programme could be transformative, especially for diesel replacement, rural energy access, and local economic development, but its impact will depend on whether it is formally integrated into the revised RUPTL and supported by a clear implementation roadmap and policy framework.
This continued reliance on fossil fuels also has fiscal implications: fossil fuel subsidies and electricity compensation continue to add pressure to the state budget, driven partly by rising global fuel prices. The 2027 state budget plans to increase energy subsidy spending by around 20% compared with the previous year.
The government's industrial policy is strengthening, rather than reducing, dependence on fossil fuels. The industrial downstreaming agenda has accelerated emissions-intensive nickel, steel, and aluminium production, driving a rapid expansion in captive coal capacity. The Ministry of Industry has published an industrial decarbonisation roadmap covering nine subsectors, which is a useful step.
However, overall, electrification and energy efficiency remain underutilised across the sector, while reliance on expensive and unreliable CCUS risks prolonging the use of fossil fuels and diverting resources away from renewables. With the EU Carbon Border Adjustment Mechanism (CBAM) entering its definitive phase, Indonesia’s low carbon price and slow industrial decarbonisation are becoming competitiveness risks for export-oriented sectors.
The forestry sector, historically contributing around 40% of national emissions, is central to Indonesia’s net zero strategy through the FOLU Net Sink 2030 target. However, after several years of decline, deforestation rates have increased again in recent years, driven by commodity-linked land conversion and food estate expansion that continue to put pressure on FOLU. Recent forest fires, intensified by El Niño, add to this pressure by generating large emissions and exposing persistent governance gaps around land clearing and peatland protection. Food security policy is still focused on large-scale land expansion, despite limited evidence that food estates address structural problems such as food distribution inefficiencies and limited access to affordable, nutritious food.
Indonesia’s transport policies present a mixed picture. EV incentives have supported recent growth, but uptake remains below government targets and highly dependent on subsidies, while limited charging infrastructure continues to constrain adoption. At the same time, Indonesia continues to rely on biodiesel as its main transport sector mitigation policy, with B50 planned for 2026 despite unresolved fiscal and sustainability risks. Public transport remains underdeveloped beyond Jakarta, and national strategies to shift freight and passenger transport modes have yet to materialise.
Buildings policy advances on paper faster than in practice. Energy management and green building regulations exist, but compliance is very low due to weak enforcement, high upfront costs and limited local government capacity. Household cooking is still dominated by LPG, while rising electricity demand from data centres could add pressure if not matched with renewable procurement and efficiency standards.
Waste remains a rapidly growing source of emissions and local pollution. Despite national targets of zero waste by 2040, source separation remains limited, open dumping and burning persist, and extended producer responsibility rules have not yet shifted practice at scale. The renewed push for waste-to-energy could reduce landfill volumes, but risks becoming a false solution if it distracts from waste prevention and upstream treatment.
Methane remains a cross-sectoral policy gap. Although the country has joined the Global Methane Pledge and launched cooperation on landfill methane and methane measurement in selected oil and gas fields, these efforts remain fragmented and do not yet amount to a coordinated methane reduction strategy, particularly for coal mine methane. This is a missed opportunity, as methane reductions could offer relatively low-cost, high-impact mitigation in the near term.
Indonesia has strengthened the legal basis for carbon market implementation, but its domestic carbon pricing still sends a weak signal and offers little incentive for real emissions reductions. Carbon pricing may be used more to monetise carbon stock, particularly as Indonesia expands its role as an Article 6 credit seller. This creates risks if credits come from weak targets or “low-hanging fruit” reductions that Indonesia will need for its own future mitigation.
Taken together, recent developments suggest that current policies are not sufficient to move Indonesia onto a 1.5°C-compatible pathway. Stronger climate action will require clearer implementation and a shift away from policies that expand fossil fuel use, increase land-use pressure, or rely on low-integrity carbon markets.
Just Energy Transition Partnership
For a more detailed analysis of this initiative, please refer to our 2024 assessment.
Launched in 2022, Indonesia’s JETP is a USD 20bn initiative backed by international partners to accelerate the power sector’s transition. The plan targets peaking on-grid emissions at 250 MtCO₂ by 2030, achieving net zero in the on-grid power system by 2050, and reaching 44% on-grid renewables by 2030. The 2023 Comprehensive Investment and Policy Plan (CIPP) outlines key Investment Focus Areas (IFAs), including early coal retirement, renewable deployment, and transmission development.
Despite its ambition, JETP implementation remains slow and has not yet become a decisive driver of Indonesia’s energy transition. Off-grid captive coal plants powering industrial zones remain outside the target framework, most funding is still loan-based with limited grant support, and the social dimension of a “just” transition remains underdeveloped.
The U.S. withdrew from the partnership in early 2025, while Germany and Japan have stepped up to co-lead the partnership (IEEFA, 2025a). From January 2026, JETP entered a new phase, with a German-funded JETP Delivery Unit replacing the former JETP Secretariat to support project tracking, stakeholder coordination, and project realisation (SIPET, 2026). By late 2025, around USD 3.1bn had been approved under the JETP framework, including the Muara Laboh geothermal expansion and Saguling floating solar plant, still far below the estimated USD 97.3bn investment needs (JETP Indonesia Secretariat, 2026).
The upcoming JETP CIPP update includes strategies to decarbonise captive coal power and build a domestic renewable energy supply chain, along with new Investment Focus Areas (IFAs) such as energy efficiency and electrification, carbon pricing instruments, and mainstreaming just transition. However, the new draft also reflects a shift in the IFAs prioritisation. In the 2023 CIPP version, early coal retirement and managed coal phase-out were positioned as the second priority, but in the new draft, these have been moved to fifth place, citing technical, legal, and financing difficulties. The cancellation of the Cirebon-1 early retirement plan further weakens JETP credibility (Mongabay, 2026a).
Because this deprioritisation contradicts the JETP's central mission, greater clarity is needed on the barriers and plans to overcome them. This could include strengthening the legal basis for coal retirement, mobilising more grant and concessional finance for project preparation and just transition measures, giving a larger role to underutilised national infrastructure financing institutions such as Sarana Multi Infrastruktur (SMI) and the Indonesia Infrastructure Guarantee Fund (IIGF), and aligning Indonesia’s taxonomy with international standards so that it does not leave room for new captive coal financing (IEEFA, 2026a).
Power sector
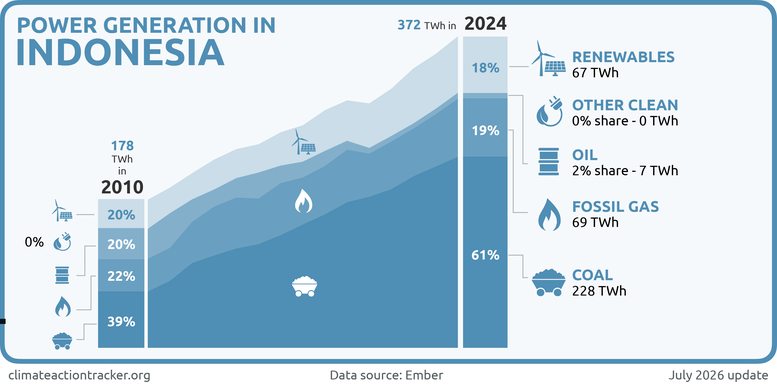
Indonesia’s power sector remains dominated by fossil fuels, with limited progress toward a renewable energy transition. Together, coal and fossil gas accounted for around 80% of total electricity generation in 2024 (Ember, 2026). Despite vast untapped potential, renewable deployment, particularly wind and solar, has been slow, and its share in electricity generation remains low (18%). The latest power plan (RUPTL 2025–2034) sets ambitious targets for renewables and storage but postpones most additions until after 2030.
Indonesia has backtracked on its early coal retirement commitment after the government cancelled the planned early retirement of PLTU Cirebon-1, the country’s most advanced pilot to date, due to high financial penalties and replacement power costs. At the same time, biomass co-firing and fossil gas continue to be promoted as transition measures despite the risk of prolonging fossil fuel dependence.
The Prabowo administration’s proposed 100 GW solar and battery programme, with around 80 GW to be developed through village cooperatives, could become a major driver of decentralised renewable energy access and local economic development if implemented well. Nuclear power is also increasingly embedded in planning, despite unresolved feasibility concerns. Overall, the sector is not on track to align with a 1.5°C pathway, which demands a faster clean energy transition.
Coal
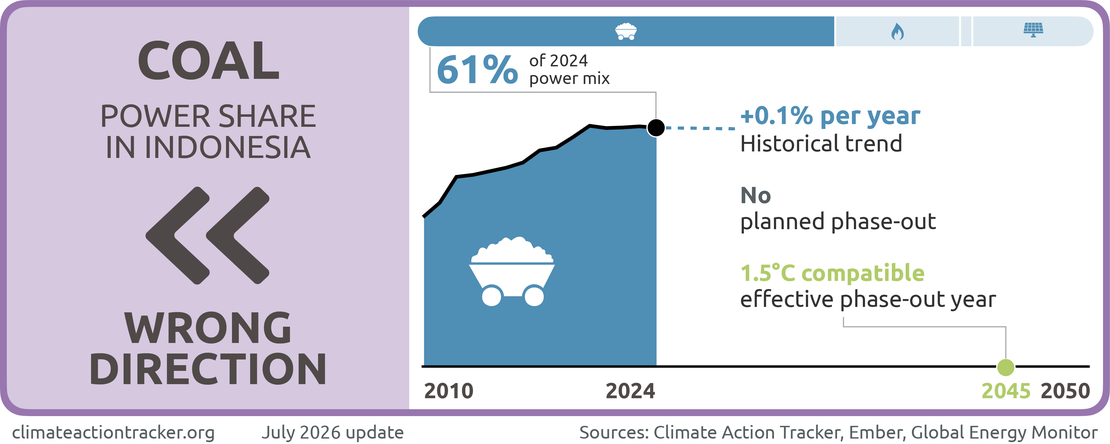
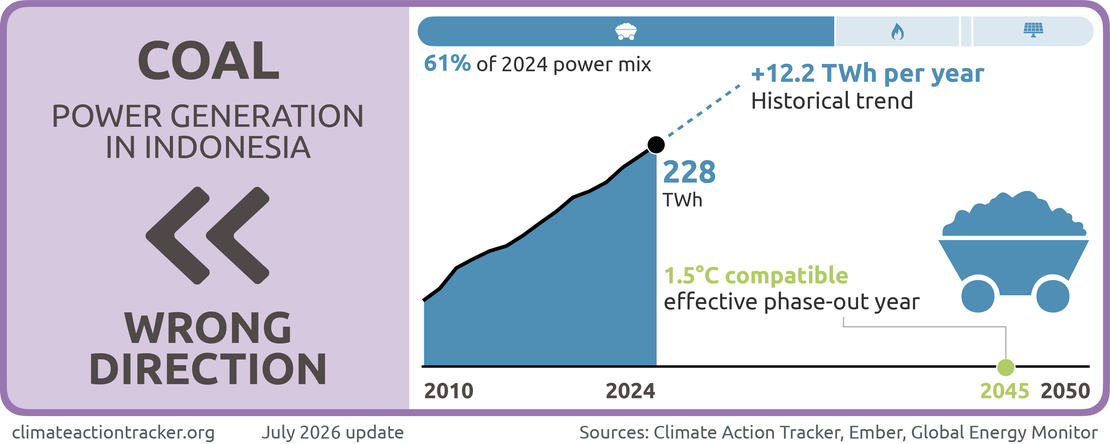
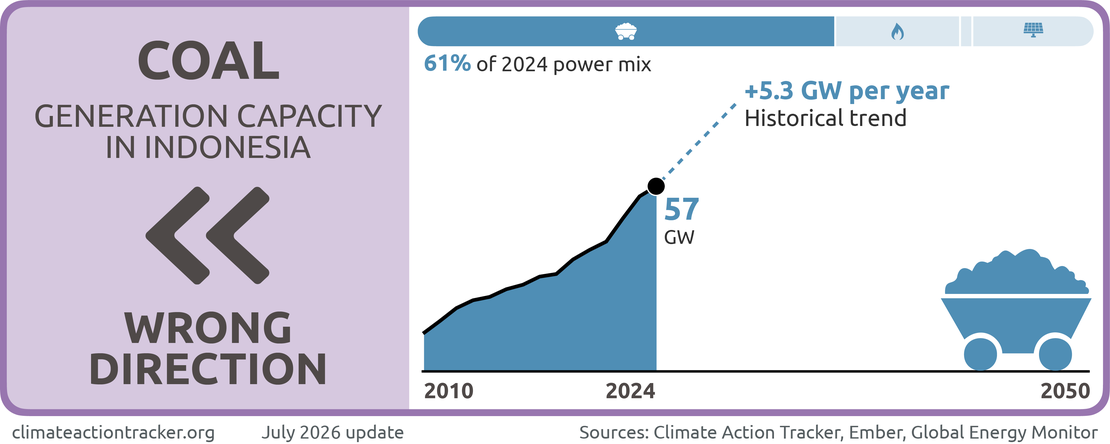
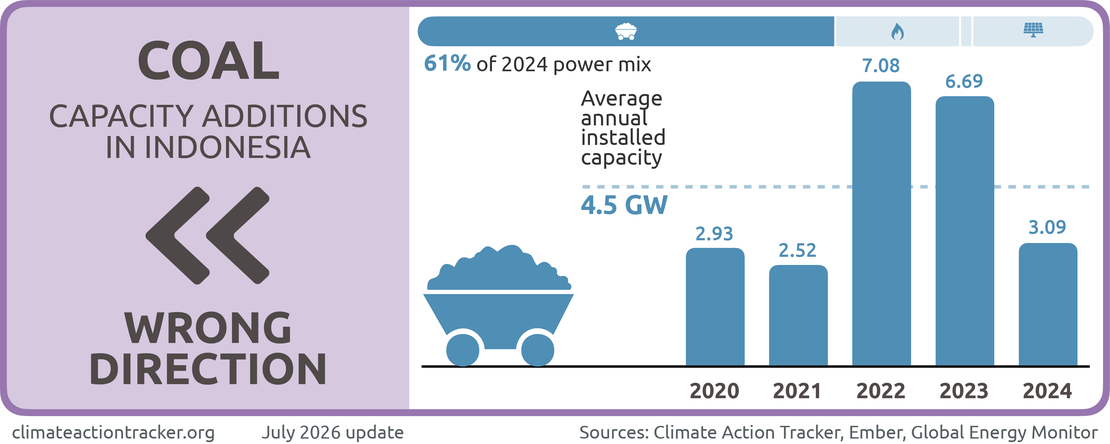
Indonesia is going in the “Wrong Direction” on coal.
Coal remains the backbone of the country’s power system, making up 62% of electricity generation in 2024. While the share of coal in the power mix has been relatively stable, actual coal-based generation has continued to rise, from 174 TWh in 2019 to 228 TWh in 2024 (Ember, 2026). As of July 2026, Indonesia has at least 61GW of operating coal-fired power plants and a further 5.3 GW under construction (Global Energy Monitor, 2026).
The Electricity Supply Business Plan (RUPTL) 2025-2034 projects that coal will still contribute 57% of electricity generation by 2030, indicating minimal change from the current state. Current projections indicate coal generation may only peak in 2037 (Ember, 2025a). In contrast, a recent CAT analysis shows that to align its power sector with a 1.5 °C trajectory, Indonesia would need to reduce the share of coal to around 29% by 2030, 4% by 2040 and fully phase it out by 2045.
Despite Presidential Regulation No. 112/2022 placing a moratorium on new coal plants (with certain exceptions) and setting 2050 as a phase-out deadline for unabated coal power, the RUPTL 2025-2034 includes frontloading 3.4 GW of new grid-connected coal by 2029 with an additional 2.8 GW capacity planned by 2034.
The new plan risks repeating past mistakes of overestimating demand growth, which previously contributed to an oversupply crisis, while locking the State Electricity Company (PLN) into costly take-or-pay coal contracts that could once again burden government finances and delay renewables deployment. This risk is particularly relevant given that the plan assumes an 8% annual GDP growth rate, yet historical trends suggest a more modest 5% (The Jakarta Post, 2025e).
Coal is also becoming harder to justify on affordability and energy security grounds. Indonesia’s coal fleet is affected by oversupply, ageing assets and underutilisation, with national coal plant utilisation at around 65% (IEEFA, 2025c). Take-or-pay contracts mean PLN continues to pay for contracted coal capacity even when plants are underutilised. PLN faces an annual gap of around IDR 33tn (USD 2bn), from paying independent power producers (IPPs) under contracted capacity factors while receiving lower actual output.
Government subsidies and compensation to PLN also rose sharply in 2024, reaching around USD 11bn, equivalent to 5% of the national budget and around one-third of PLN’s revenue (IEEFA, 2025c). Recent blackouts that hit the Java-Madura-Bali grid show that domestic coal abundance does not guarantee secure supply: many PLN plants require medium-calorific coal, while domestic production has shifted towards lower-calorific grades.
At the same time, PLN faced procurement gaps and domestic market obligation (DMO) price distortions, which make domestic supply less attractive than exports (Asia Times, 2026; The Jakarta Post, 2026n). These issues serve as a reminder that Indonesia’s centralised, coal-dependent power system is vulnerable to fuel supply disruption, which strengthens the case for decentralised renewable energy systems such as rooftop solar (IEEFA, 2026b; Mongabay, 2026b).
Indonesia signed on to part of the Coal Exit at COP26, committing to Clause 2 (phasing out coal by the 2040s) but not Clause 3 (no new plants). In 2024, the President made ambitious announcements at various high-level international fora about the country's energy transition, pledging to retire all fossil fuel and coal-powered plants within 15 years (Reuters, 2024b). These announcements remain inconsistent with continued coal expansion and the lack of concrete early coal retirement plans.
While Presidential Regulation No. 112/2022 and MEMR Regulation No. 10/2025 provide the legal basis for early coal retirement, its implementation remains uncertain. The latter regulation does not publish an official list of coal-fired power plants eligible for early retirement but mainly outlines the procedures for implementing such processes. It also treats funding availability as a precondition, shifting the focus away from accelerating early coal retirement and towards managing financial risks (IESR, 2025a).
The most advanced pilot was the planned early retirement of PLTU Cirebon-1 under the ADB’s Energy Transition Mechanism (ETM), a 660 MW plant expected to retire in 2035, seven years ahead of schedule. However, in 2025, the government decided not to proceed, citing concerns over potential IDR 130tn in penalty and replacement power costs (The Jakarta Post, 2025b). Authorities have instead signalled a shift toward reviewing older, less efficient units, further emphasising the pivot away from a clear “phase-out” pathway toward a more limited “phase-down” approach (Reuters, 2025b; The Jakarta Post, 2025c).
PLN continues to promote biomass co-firing as a mitigation measure, but it is unlikely to offer a credible way out of coal dependence. Co-firing would only marginally reduce coal use and could delay more structural measures such as early retirement, flexible dispatch, or repurposing coal sites for renewables and storage (NewClimate Institute and I4CE, 2024; IEEFA, 2025c). Its climate and air quality benefits are also limited and not transparently accounted for, as lifecycle emissions from land use change, processing, transport, and handling are often excluded (CREA, 2025a).
Scaling biomass production could create additional ecological and social pressures, particularly if it relies on monoculture energy plantation forests (Mongabay, 2026b). Especially without a clear coal retirement pathway, biomass co-firing risks locking in coal infrastructure rather than a genuine transition measure.
Fossil gas
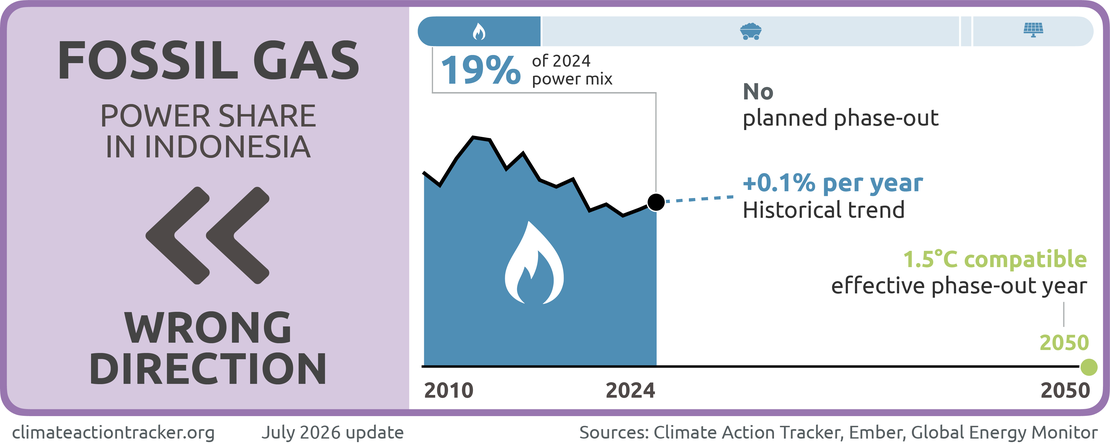
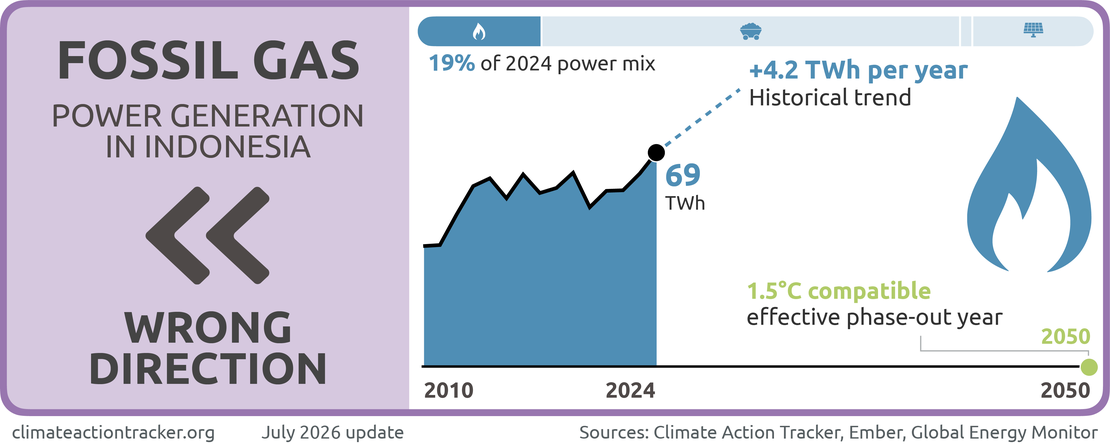
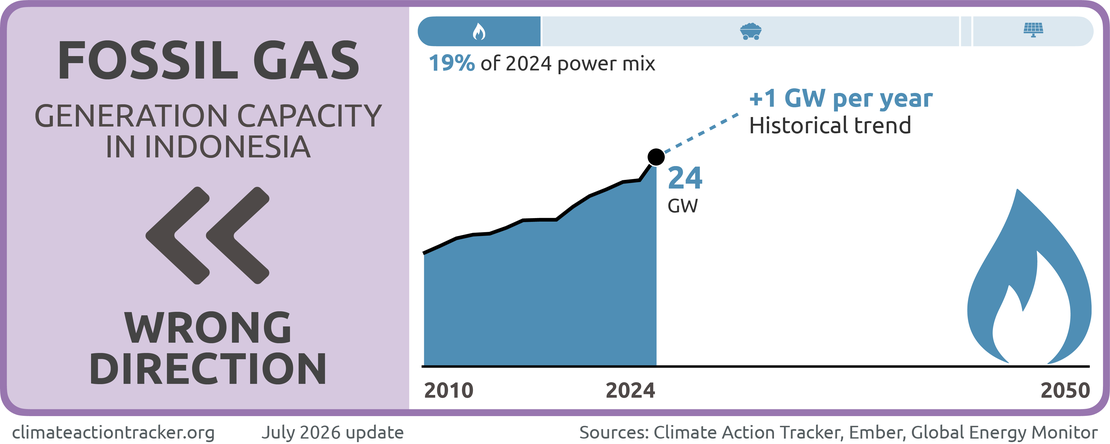
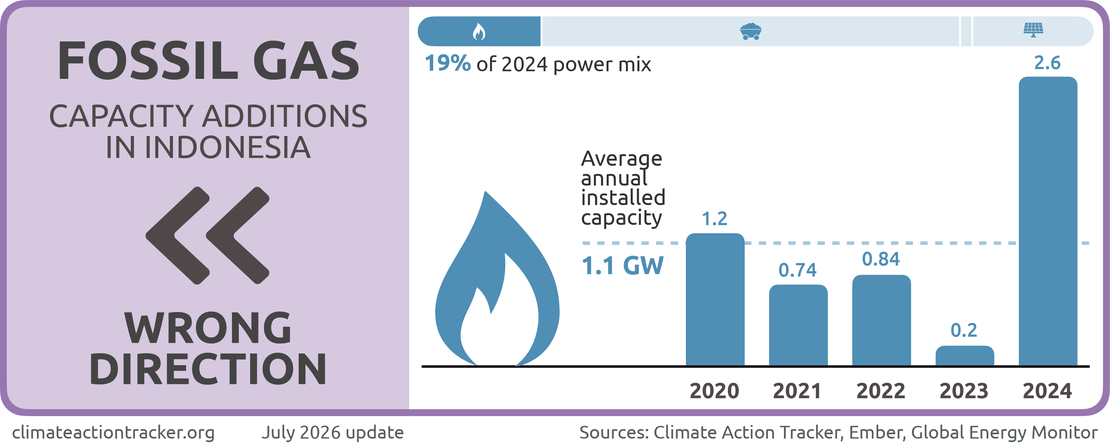
Indonesia is going in the “Wrong Direction” on fossil gas.
The share of fossil gas in Indonesia’s power mix has remained broadly stable over the past five years, standing at 19% in 2024. However, absolute gas‑fired electricity generation has continued to increase over the same period, aside from the temporary decline in 2020 following the COVID‑19 pandemic (Ember, 2026)
The RUPTL 2025-2034 positions fossil gas as a key “transition fuel”, with plans to add 9.3 GW of new gas-fired power capacity by 2029 and an additional 1.2 GW by 2034, leading the country to long-term fossil infrastructure lock-in. Under the latest RUPTL, the share of fossil gas in the power generation mix is gradually projected to increase to 23% by 2030, then plateau at around 21–23% through 2034.
The role of fossil gas is also being reinforced through the Japan-led Asia Zero Emission Community (AZEC), where several Indonesia-Japan transition cooperation projects focus on LNG value-chain development, combined cycle gas turbine (CCGT) feasibility studies, and coal-to-gas conversion, raising concerns that fossil gas-oriented cooperation could deepen infrastructure lock-in and even undermine Indonesia’s economic and environmental interests (CELIOS and Greenpeace Indonesia, 2025).
While often—and wrongly—framed as a cleaner alternative to coal, this large-scale fossil gas expansion is not aligned with CAT benchmarks for a 1.5°C aligned power sector, which would require Indonesia's electricity share from fossil gas to be capped at 9% by 2030 and 4% by 2035, with all unabated fossil gas fully phased out by 2045.
This pathway carries significant financial and operational risks. Global gas prices are high and volatile, infrastructure investments are long-term, and large-scale expansion could expose Indonesia to price shocks, more costly power generation, and increased state financial burden due to heavily subsidised electricity. Continued reliance on fossil gas could cost Indonesia around USD 60 billion in subsidies and compensation to PLN over the next decade (IEEFA, 2025b). Furthermore, the expansion is questionable from an efficiency standpoint, as Indonesia's existing gas fleet is already severely underutilised, operating at an average capacity factor of only 30% in 2024.
Renewables
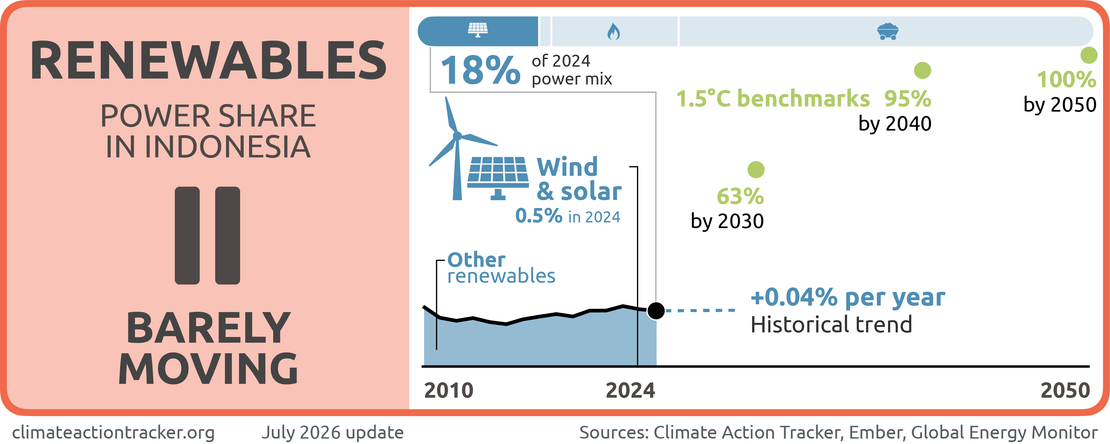
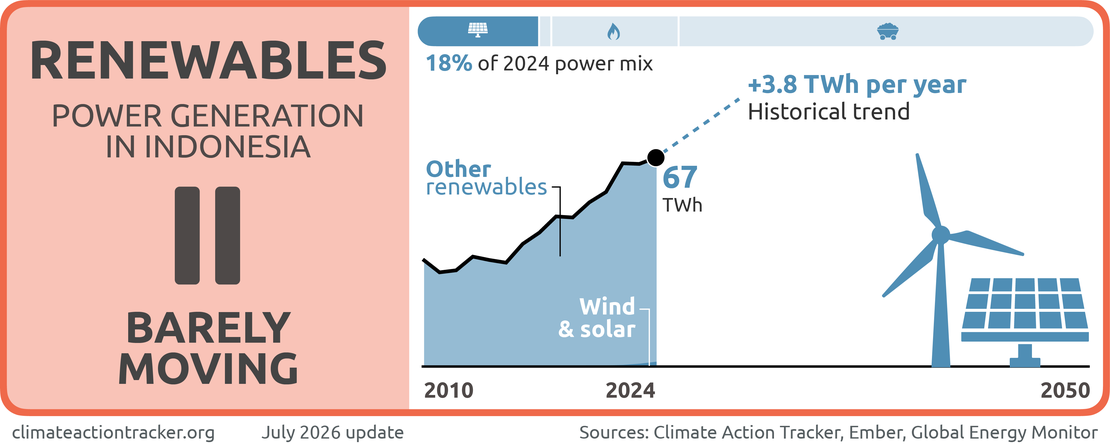
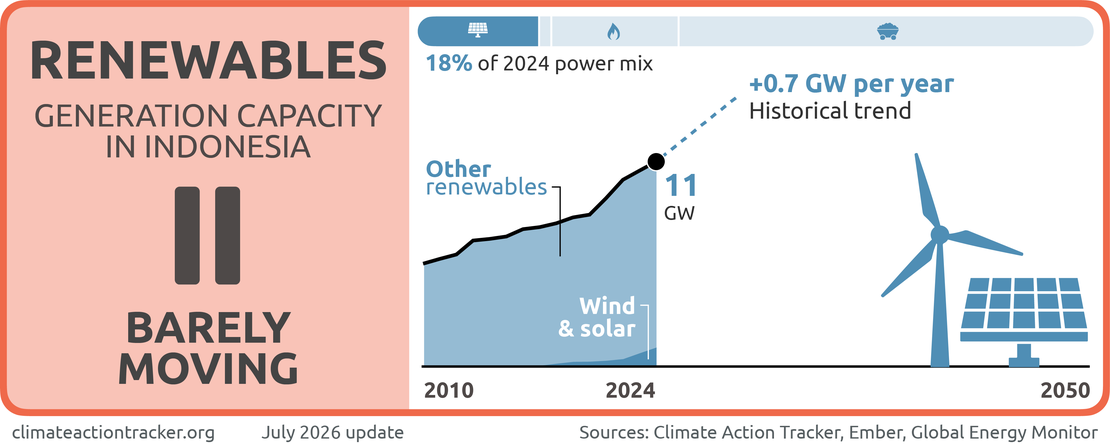
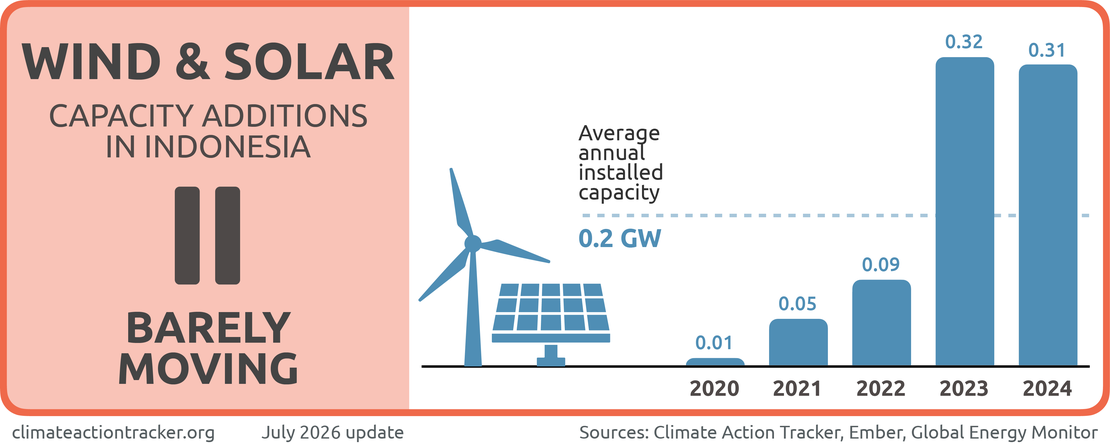
Indonesia’s renewable energy policy is sending “Mixed Signals”.
Indonesia possesses some of the world’s largest untapped renewable energy resources, with MEMR estimating a technical potential of 3,294 GW for solar, 95 GW for hydro, 155 GW for wind (on- and offshore), 57 GW for bioenergy, 24 GW for geothermal, and 63 GW for wave power (MEMR, 2023a, 2024b). Despite this vast potential, deployment remains sluggish, with renewables accounting for only around 18% of total electricity generation in 2024, largely dominated by hydropower and bioenergy (Ember, 2026). In fact, between 2015 and 2024, Indonesia added only 4.4 GW of renewable capacity, compared with 25.9 GW of fossil fuel power plants (The Jakarta Post, 2026k). More importantly, wind and solar remain almost non-existent in Indonesia’s power sector, representing less than 1% of generation in 2024. By 2024, the country had installed only about 1 GW of solar and wind capacity, together generating less than 1% of total electricity (Ember, 2026).
The RUPTL 2025-2034 sets a headline target of 42.6 GW of new renewable capacity and 10.3 GW of energy storage by 2034, with a strong focus on solar (17.2 GW) and hydro (11.7 GW). However, even if fully implemented, renewables would only make up about 20% of electricity generation by 2030 and slightly over 30% by 2035. This pace falls far short of what’s needed to align with CAT benchmarks for a 1.5°C-aligned power sector, which requires renewables to reach around 57-69% of electricity generation by 2030, 84-88% by 2035, and 100% by 2050. The targets also fall behind Indonesia’s JETP goals, which aim for 44% renewable on-grid power by 2030 and 92% by 2050, alongside a net zero power system by mid-century.
A critical issue with the new RUPTL is that renewable energy development is heavily backloaded, with over 70% of planned projects scheduled for the second half of the plan’s period (2030–2034). This approach, combined with the PLN's poor track record of meeting past renewable targets, raises concerns among investors about execution risks and regulatory inconsistency (IEEFA, 2025b). If projected electricity demand and GDP growth (assumed at 8% annually) fail to materialise, PLN risks yet another oversupply crisis, which would crowd out renewables from accessing an already saturated grid (The Jakarta Post, 2025e).
Transmission bottlenecks further hinder renewable deployment. Sumatra, for instance, has surplus capacity and vast untapped renewables potential, but lacks sufficient interconnection between regions. Sulawesi presents a similar case: while North Sulawesi has an excess renewable supply, major energy demand comes from industrial zones in Central Sulawesi, which remain poorly connected. Indonesia’s slow renewable energy development can be partially attributed to the geographic mismatch between demand centres in Java and renewable potential across the archipelago, compounded by the country’s inability to distribute them effectively (CREA, 2025b; The Jakarta Post, 2025d).
Unlocking this potential will require not just increased capacity, but major investment in transmission infrastructure and system-wide planning. Around USD 35bn will be needed to realise transmission and distribution projects in RUPTL 2025–2034, but PLN’s low net profit margin and internal rate of returns make financing difficult (IESR, 2025a). In parallel, decentralised renewables such as rooftop solar paired with battery storage could reduce pressure on long-distance transmission while improving energy resilience (IEEFA, 2026c).
The Prabowo administration’s proposed 100 GW solar and battery programme, if implemented well, could be transformative for replacing diesel plants, improving rural energy access, and promoting productive uses that support local economic development. The programme is reportedly being accelerated from five years to three years in response to energy supply disruptions linked to the partial closure of the Strait of Hormuz amid the war in the Gulf region (IESR, 2026c). The programme now targets implementation in 2026–2028, with an initial 13 GW rollout focused on areas with existing distribution networks and around 80 GW to be developed through village cooperatives (ANTARA News, 2026a; Humanis Foundation, 2026; The Jakarta Post, 2026a).
Recent developments suggest the programme is beginning to move beyond political announcement, as the government has launched an initial portfolio of 14 solar projects totalling 5.3 GWp and stated that the 100 GW target will be incorporated into a revised RUPTL (Cabinet Secretariat of the Republic of Indonesia, 2026; CNBC Indonesia, 2026). This is a positive step, especially given the programme’s scale nearly equals the RUKN’s 2060 solar target of 109 GW (IESR, 2025a). Nonetheless, its credibility will ultimately depend on whether the revised planning framework is formally adopted and accompanied by a clear implementation roadmap and supportive policies.
Recent policy changes send mixed signals for renewable deployment. MEMR Regulation No. 5/2025 provides greater legal clarity for renewable PPAs, including fixed pricing, clearer risk allocation, carbon credit provisions and longer contract terms, which could improve investment certainty. The relaxation of solar local content requirements in 2024, which reduced the minimum threshold from 40–60% to 20% with conditional exemptions, could also help reduce project delays and costs, while supporting domestic supply chain development.
At the same time, the long overdue New and Renewable Energy Bill remains stalled due to disagreement over power wheeling (a mechanism that would allow private power producers to sell electricity directly to consumers using PLN’s grid) and the inclusion of coal derivatives. Rooftop solar policy has also been weakened; the removal of net metering and its replacement with a quota-based system reduces incentives for both residential and industrial users. Although the government is considering increasing the 2026 rooftop solar quota by 400 MW to around 1,400 MW, Indonesia remains far behind regional peers, with only around 853 MW installed by 2025 compared with 6.9 GW in Viet Nam, 3.6 GW in Thailand, and 1.8 GW in Malaysia (IEEFA, 2026b; The Jakarta Post, 2026i).
Nuclear
Nuclear is increasingly embedded in Indonesia’s energy planning, despite unresolved feasibility concerns. The National Long-Term Development Plan (RPJPN) 2025-2045, National Electricity Master Plan (RUKN) 2024-2060, and RUPTL 2025-2034 all include plans to integrate nuclear power into Indonesia’s energy mix as a baseload source, as part of the country’s efforts to achieve net zero emissions by 2060. The National Energy Policy (KEN) 2025 projects nuclear to reach 12% of primary energy by 2060, marking a shift from the previous “last resort” framing (Tempo, 2025b). Indonesia aims to operate its first nuclear power plants by 2033, with two proposed sites in Sumatra and Kalimantan, each with a planned capacity of 250 MW (World Nuclear Association, 2026).
Although nuclear power does not emit CO2, the CAT doesn’t consider it a viable climate solution. This is due to a range of risks and limitations, including the potential for accidents and proliferation, escalating costs compared to increasingly competitive renewables, long construction timelines, increased vulnerability due to the intensifying impacts of climate disasters, and its incompatibility with the flexible electricity supply needed to balance variable sources like wind and solar. These challenges are compounded by Indonesia’s location on the seismically active Pacific “Ring of Fire”, which raises serious safety concerns.
Nuclear projects also carry substantial financial risks. High upfront capital and future decommissioning costs imply that plants would likely require large government subsidies. Since much of the equipment and services would be priced in foreign currencies, nuclear development could also expose Indonesia to currency and fiscal risks. Prioritising nuclear could divert limited public finance and institutional capacity away from renewables, energy storage, and grid investments that are already commercially available and faster to deploy.
Industry
Industrial emissions have nearly doubled since 2014, exceeding 480 MtCO₂e in 2024, driven largely by rising coal use (IESR, 2025a). Industrial energy demand has grown rapidly over the past decade, and during the same period, the sector’s energy mix shifted more heavily toward coal, which supplied almost 60% of the sector’s energy demand (IESR, 2025a). The government’s downstreaming agenda, while central to Indonesia’s ambitious economic growth target, has reinforced the sector’s heavy reliance on coal and fossil gas, presenting serious challenges for decarbonisation.
Indonesia’s RUKN 2024–2060, which sets the direction for the RUPTL 2025–2034, includes plans to add over 20 GW of captive coal for industrial users, particularly smelters, which could increase captive coal capacity by 180% through 2031 (Ember, 2025a). Captive plants also fall outside the government’s capped coal price, making them more expensive and increasingly uncompetitive compared to renewables (Energy Tracker Asia, 2025).
At the heart of this expansion is the nickel industry, which underpins Indonesia’s ambitions to build a domestic battery supply chain. Captive coal capacity for nickel smelters skyrocketed from 1.4 GW in 2013 to 10.8 GW in 2023 (KADIN Indonesia, 2024). The figure in the new JETP CIPP draft is even higher, reporting 19.7 GW of operating captive coal capacity in 2024, with a pipeline of captive coal power projects under development totalling nearly 9 GW by 2030. More recent estimates suggest that operational and planned captive coal capacity has reached around 31 GW, including 19.3 GW operating, 3.6 GW under construction, and an additional 8.2 GW planned (CREA and GEM, 2026).
As a result, domestically-produced nickel has an emissions intensity of 58.6 tCO₂e per tonne, which is 22–40% higher than the global average and far above the <20 tCO₂e/tonne benchmark for low-carbon nickel (IESR, 2024). ESG concerns around deforestation, water pollution, and social conflict further threaten the global competitiveness of Indonesian nickel, and recent foreign investment withdrawals should serve as a wake-up call (The Diplomat, 2024; Mongabay, 2025b; The Jakarta Post, 2025f). The fossil lock-in risk from nickel downstreaming could also be repeated in aluminium, where planned downstreaming may add a further 9.8 GW of captive coal capacity (CREA, 2026).
The Ministry of Industry has publishedan industrial decarbonisation roadmap covering nine subsectors: cement, iron and steel, fertilisers, chemicals, pulp and paper, textiles, glass and ceramics, automotive, and food and beverages. The roadmap sets out a pathway to reduce industrial emissions by around 67 MtCO₂e by 2035 and 290 MtCO₂e by 2050.
The roadmap identifies energy and material efficiency, fuel and material substitution with lower-carbon alternatives, technology and production process modernisation, low-carbon electricity and electrification, and CCUS as key measures, and estimates that industrial decarbonisation would require around USD 260bn in investment between 2025 and 2050. Place-based initiatives such as the Net Zero Industrial Precincts programme and pilots at Weda Bay and Morowali could help operationalise this decarbonisation roadmap (Climateworks Centre, 2025; UNIDO, 2026).
Electrification and energy efficiency remain critical but underutilised pillars of industrial decarbonisation. Electricity’s share in industrial energy demand remains low, even though electrification can reduce direct Scope 1 emissions if supplied by low-carbon electricity. Industrial heat pumps may already be cost-competitive for low-temperature heat in some sectors, especially where waste heat is available (IESR, 2025a) Energy efficiency progress also remains very slow: in 2023, the average year-on-year improvement across industrial sub-sectors was just 0.07% (IESR, 2024), far below the 4% annual rate recommended by the IEA (IEA, 2023b).
External pressure is also increasing. The EU Carbon Border Adjustment Mechanism (CBAM), entering its definitive phase in 2026, will directly affect Indonesian exports of cement, iron and steel, aluminium and fertilisers (IESR, 2025a). CBAM could impose a tariff burden of up to 0.021% of Indonesia’s 2022 GDP if Indonesian commodities remain more carbon-intensive than EU benchmarks (World Bank, 2025). Accordingly, industrial decarbonisation might no longer be only a climate policy issue, but also a competitiveness issue for Indonesia’s export-oriented sectors.
Indonesia introduced a regulatory framework for carbon capture and storage (CCS) in 2024, creating a legal basis for CC(U)S projects and opening the door to private investment across oil and gas, power generation and energy‑intensive industrial sectors. This framework has been welcomed by fossil fuel interests as a way to justify continued use under “hard-to-abate” narratives (Climate Analytics, 2025). CCS technology refers to engineered methods to capture CO₂ from a source and store it geologically. However, these technologies are neither commercially viable nor proven at scale. Their use should be limited to industrial applications where there are fewer options to reduce process emissions, rather than prolonging the use of fossil fuels in the power sector, where cost-effective renewable alternatives exist.
Transport
Indonesia’s transport sector is the third-largest contributor to energy-related CO₂ emissions, accounting for approximately a quarter of national emissions (IESR, 2026a). The sector is still on a rising emissions trajectory:
- Transport emissions are projected to keep rising under current policies and could more than double after 2050, driven by continued mobility growth and rising vehicle ownership (IESR, 2025a).
- Passenger transport remains the largest source of sectoral emissions, accounting for around 70% of transport emissions in 2024, with motorcycles and cars as the main contributors.
- Freight contributes around 30% of sectoral emissions, dominated by diesel-powered trucks (IESR, 2025a, 2026e).
Current transport decarbonisation policies remain fragmented: Minister of Transportation Decree No. 8/2023 sets out climate change mitigation actions in the transport sector to deliver the NDC, but no further implementation updates have been published as of 2025 (IESR, 2025a).
Biofuels
Indonesia continues to rely heavily on biofuels as its main transport mitigation policy. The mandatory blending rate has increased from 15% (B15) in 2015 to 35% (B35) in 2023, to 40% (B40) in 2025 and 50% (B50) in 2026 (Coordinating Ministry for Economic Affairs, 2023; BioEnergy Times, 2024; S&P Global, 2024). B50 was formally launched on 1 July 2026, three years earlier than initially planned, with full nationwide distribution targeted for October 2026 (CNN Indonesia, 2026; The Jakarta Post, 2026h).
The policy is increasingly framed as an energy security measure to reduce diesel imports and exposure to global oil price shocks, particularly amid the recent energy crisis, but its climate benefits remain uncertain because it relies on palm oil as a feedstock, which could shift emissions pressure from the transport sector to the land sector (IESR, 2026c; The Jakarta Post, 2026r, 2026p).
Higher biodiesel blending faces fiscal, supply, and sustainability risks. Palm oil plantations remain a major driver of deforestation (see Forestry section), and achieving B50 could require at least 2.8 million hectares of oil palm cultivation, or up to 5.4 million hectares by early 2040 under an aggressive scenario (IESR, 2024; Satya Bumi et al., 2024). Biodiesel
refineries are already operating at around 85% capacity, and moving beyond B40 would require new capacity or technology.
Nearly 95% of palm oil export levy funds already go to biodiesel subsidies, leaving limited support for upstream productivity improvements, especially for smallholders (IESR, 2025a). Without stronger productivity gains and safeguards, additional palm oil demand could increase pressure on forests, intensify land conflicts and push up food prices (Tempo, 2026a; The Jakarta Post, 2026r).
In contrast, bioethanol uptake has been slow. Although MEMR Regulation No. 12/2015 outlined a 5% blending target (E5) by 2020 and a 20% blending target (E20) by 2025 (now postponed to 2028), blending was essentially zero between 2018 and 2022 (ERIA, 2024). In 2023, Pertamina introduced Pertamax Green 95 (E5), now available at select refuelling stations in Jakarta and Surabaya (MEMR, 2023b, 2024a).
However, Indonesia’s domestic production capacity remains far below what would be needed for nationwide implementation. Scaling up bioethanol would require either a significant expansion of sugarcane plantations, raising similar concerns over land-use change and food security, or greater reliance on imported sugarcane and bioethanol, which would undermine the energy security rationale (IESR, 2024).
Sustainable aviation fuel (SAF) is becoming more relevant as aviation emissions rise. Aviation accounted for around 7% of transport emissions in 2024, and air travel is especially important in eastern Indonesia, where modal alternatives are limited (IESR, 2025a). Indonesia’s SAF roadmap targets 1% blending by 2027, 2.5% by 2030 and 50% by 2060, but previous SAF targets were missed. Feedstock availability, high production costs, and weak demand-side enforcement remain major barriers (IESR, 2025a).
Electric vehicles
EV uptake has been accelerating over the past five years, but progress remains uneven across vehicle segments and highly incentive-driven. Indonesia’s EV stock reached around 234,000 electric four-wheelers (E4Ws) and 162,000 electric two-wheelers (E2Ws) in 2025, suggesting that adoption remains concentrated in private mobility, while commercial and public fleet segments such as buses and freight vehicles remain at an early stage (IESR, 2026b). This remains far below Indonesia’s 2030 targets of 13 million E2Ws and 2 million E4Ws (Indonesian Ministry of Energy and Mineral Resources, 2024). Indonesia’s E4W sales share could reach 25% by 2030, but the resulting stock of almost 1 million E4Ws would still be less than half of the government’s 2 million target (IEA, 2025a).
Government incentives have played a central role in this growth. Since 2023, electric cars and buses have benefited from a VAT reduction from 11% to 1%, while import duties have been waived for manufacturers committing to local production (IEA, 2025a). Overall EV incentives increased from around IDR 2.1tn in 2023 to IDR 29.1tn in 2025, with import and luxury tax exemptions accounting for most support. In 2024, the majority of E2W and E4W sales were supported by incentives. E2W sales fell by more than 80% year-on-year in Q1 2025 after the previous purchase subsidy ended at the end of 2024 (IESR, 2025a, 2026b).
The government is considering renewed purchase subsidies for E2Ws, but the proposed IDR 3mn (USD 170) per unit may be insufficient to encourage a shift from conventional motorcycles to E2Ws (The Jakarta Post, 2026o). The government has also discussed scaling E2W conversion from around 200,000 units per year to 6 million units per year in response to oil price shocks and fuel import dependence (The Jakarta Post, 2026b, 2026m). However, such a rapid scale-up appears unrealistic without a stronger ecosystem, given that previous annual targets were missed and certified workshop capacity remains far below what would be needed for mass conversion (IESR, 2026c).
Sales incentives alone will not be sufficient. To align with the CAT Paris-aligned sectoral benchmarks, Indonesia would need to phase out internal combustion vehicle sales before 2035 and ensure that EVs account for at least 95% of new vehicle sales by 2030, with EVs comprising 10-45% of the total vehicle stock by that year. In addition, reaching net zero around 2060 would require imposing an ICE sales ban by 2040 and combining it with age limits and scrappage policies for cars and motorcycles (IESR, 2025a).
Indonesia is shifting EV policy from import incentives to local production. Import tax breaks for EVs ended in late 2025, while foreign car manufacturers are expected to begin local production in 2026 under commitments to match imported volumes with domestic production and meet local content requirements (The Jakarta Post, 2026c). This shift could support domestic industry and battery supply-chain development, but a premature move away from import incentives could slow EV adoption if locally produced EVs are not yet cost-competitive or available at sufficient scale.
Charging infrastructure is expanding, but deployment still needs to better reflect user behaviour and regional needs. Indonesia had 4,778 public charging stations and 2,240 battery swapping stations in 2025, but battery swapping growth has slowed, while charging station deployment continues to expand (IESR, 2026b). Home charging dominates E4W electricity use, with 2024 home charging around three times higher than public charging, which means residential grid readiness is becoming increasingly important. Public charging is also still concentrated in Java and Bali, while eastern Indonesia remains underserved, which could limit EV adoption outside major urban markets (IESR, 2026b).
Smart charging and vehicle-to-grid (V2G), particularly when coupled with solar PV, could help manage the grid impacts of higher EV uptake, but Indonesia is not yet prepared to capture these benefits. Realising this would require building a whole new ecosystem, from digitalised charging infrastructure and tariff design to regulatory clarity and pilot projects in urban centres (IESR, 2025a).
Public transit and freight transport
Public transport remains underdeveloped outside Jakarta, mainly due to the constrained fiscal capacity of many subnational governments. Nationally, public transport modal share accounts for only around 2–5%, compared with around 10% in Greater Jakarta (Almaputri, 2019; WRI Indonesia, 2024; IESR, 2025b). Greater Jakarta’s relatively higher modal share reflects sustained policy commitment and investment in its mass transit systems, including TransJakarta, KRL commuter rail, MRT and LRT. Expanding reliable public transport beyond Jakarta is critical to reduce transport emissions, as passenger transport remains the sector’s largest emissions source.
Existing modal shift programmes remain too small to change the sector’s emissions trajectory. The Buy the Service (BTS) programme, a government-funded scheme that pays operators to run bus services on selected routes, has helped shift some users away from motorcycles, but it faces continuity risks as several services have been transferred to regional government responsibility, where fiscal capacity is more limited. Its planned 2025 expansion, supported by IDR 177bn across 12 corridors, is therefore a useful step but still far from the scale needed (IESR, 2025a).
Bus electrification is progressing but remains concentrated in a few cities. Only around 870 electric buses are currently operating in Indonesia, with TransJakarta alone accounting for around 500 of them (Detik News, 2026a; Investor Trust, 2026). This remains far below the Ministry of Transportation’s target to electrify 90% of urban mass public transport by 2030, equivalent to around 45,000 electric buses (IESR, 2025a). Costs remain a key barrier, as electric buses are still more expensive than diesel and biodiesel buses today, partly because fossil and biodiesel buses benefit from fuel subsidies (IESR, 2025a).
Freight transport remains heavily road-dependent, with little diversification away from diesel-powered trucks. Trucks carry over more than 90% of total goods and produce around 30% of transport GHG emissions, despite making up less than 4% of road vehicles (IESR, 2026a). Biodiesel blending is the main mitigation strategy, while battery-electric trucks remain at an early stage in Indonesia, despite being more mature and closer to cost-competitiveness than its hydrogen-based alternatives (IESR, 2024; IEA, 2025a). Shifting long-haul freight to rail could reduce emissions, congestion, road accidents and road damage, but rail freight remains marginal, particularly in Java, due to higher costs, slower transit times and reliability constraints (GIZ, 2021).
Freight decarbonisation will also require last-mile electrification and charging strategies tailored to different vehicle uses. Electric logistics fleets remain below 2% in Indonesia, even though electrifying vans and two-wheelers could reduce urban emissions and improve air quality (IESR, 2026e). Rail decarbonisation should prioritise overhead catenary systems for high-traffic corridors and the use of more flexible technologies such as battery systems for lower-traffic lines (IESR, 2026e).
Forestry
Indonesia’s land-use, land-use change and forestry (LULUCF) sector has historically been a major contributor to national emissions, accounting for around 40% of total GHG emissions on average over the past 20 years (Gütschow et al., 2025; Government of Indonesia, 2026). As the world’s largest palm oil exporter, it comes as no surprise that the biggest driver of deforestation is agricultural and commodity-driven land conversion (Global Forest Watch, 2026). This pressure is likely to intensify with the current government’s 8% economic growth ambition, which relies heavily on extractive industries and large-scale agricultural and plantation projects (Reuters, 2026).
While deforestation rates declined from 2016 to 2021, recent data suggest this trend has reversed. In 2025, deforestation, understood as the permanent or long-term conversion of forest into another land use, reached around 434,000 ha, a 66% increase from 2024, with increases recorded across all major islands (Auriga Nusantara, 2026). Tree cover loss, a broader indicator that captures temporary canopy loss from fire or plantation cycles, also increased from 0.89 Mha in 2022 to 1.2 Mha in 2025 (Global Forest Watch, 2026; Reuters, 2026), following the end of the moratorium on new palm oil plantations in 2021 (Reuters, 2024a).
Slash-and-burn remains a common and cheap method for land clearing, significantly contributing to LULUCF emissions. The 2026 wildfires show how this risk can be amplified when dry conditions are combined with weak enforcement: between January and July 2026, around 286,000 ha burned across Indonesia, including around 68,000 ha inside industrial concessions. By late August, the total burned area had reportedly reached nearly 900,000 ha, roughly four times the size of Tokyo, while Indonesia’s year-to-date fire emissions had reached 76.2 Mt of carbon, around one-third of the global total (The Jakarta Post, 2026s). Although El Niño can intensify fire risks, repeated burning in concessions and peatlands points to persistent governance gaps around land clearing and peatland protection (The Jakarta Post, 2026q).
These recent increases in deforestation, tree cover loss and fire-related emissions put the FOLU Net Sink by 2030 target at risk. The government aims for the LULUCF sector to reach net negative emissions of 140 MtCO₂e by 2030 and 304 MtCO₂e by 2050, to be achieved through the prevention of deforestation, conservation of natural forests, sustainable forest management, and enhancing carbon sinks from peatlands and mangroves. The target is anchored in Presidential Regulation No. 98/2021 and operationalised through the FOLU Net Sink 2030 Operational Plan, which was stipulated by Minister of Environment and Forestry Decree No. 168/2022. Indonesia’s net zero 2060 strategy largely hinges on FOLU becoming a sustained net sink in the following decades.
Research warns that forest mitigation potential may be overestimated if climate and disturbance risks are not fully accounted for, as climate change and land-use history can reduce or even reverse carbon sinks into sources, highlighting the risks of over-reliance on FOLU in climate mitigation plans (Anderegg et al., 2020; Albrich et al., 2023). To reach a FOLU net sink by 2030 and net zero by 2060, Indonesia needs stronger policies to halt deforestation and expand reforestation. Current policies are not compatible with these goals; the government will likely need to explore alternative development pathways that align with lower emissions and reduced land-use change, such as electrifying transport demand and limiting palm oil use for biofuels.
Recent climate-related disasters have made the cost of deforestation more visible. The deadly floods and landslides in Aceh, North Sumatra and West Sumatra in late 2025, which displaced around 400,000 people and killed more than 1,000, were triggered by extreme rainfall and a rare tropical storm, but forest loss and degraded watersheds likely worsened the impacts by reducing soil absorption, increasing runoff and destabilising slopes (The Jakarta Post, 2025a; Detik News, 2026b). Following the disaster, the government revoked permits for 28 companies holding plantation, mining and power plant concessions allegedly linked to environmental degradation, but restoration plans remain unclear (The Jakarta Post, 2026f).
International partners continue to play a vital role through results-based financing mechanisms like the Reduce Emissions from Deforestation and Forest Degradation (REDD+). As of October 2025, USD 499.8 m has been committed to the country under the results-based payment system, of which USD 340.7m had been disbursed, including USD 103.8m from the Green Climate Fund through UNDP (UNDP, 2025).
As home to the world’s third-largest tropical rainforest, Indonesia could become one of the main beneficiaries of the Tropical Forests Forever Facility, a Brazil-led financing mechanism launched at COP30 to reward tropical forest countries for conservation. The facility aims to mobilise USD 125bn in investment capital and provide payments of up to USD 4/ha/year, while applying a discount mechanism for forest loss (Madani Berkelanjutan, 2026).
Its effectiveness remains to be seen as the fund had reportedly raised only USD 6.7bn in sponsor capital, below the USD 25bn needed for full-scale rollout. Payments also depend on investment returns after investors and sponsors are repaid, which could weaken the fiscal incentive for forest protection if market returns are lower than expected (Mongabay, 2025a).
Blue carbon
On a related note, the 2035 NDC introduces marine conservation as a mitigation measure, supported by the Ministry of Marine Affairs and Fisheries Decree No. 52/2024 and Regulation No. 1/2025 on the governance of carbon economic value in the marine sector. To facilitate the integration of this new sector, the government launched the Blue Carbon Ecosystems in Indonesia Roadmap and Action Guide at COP30. While blue carbon conservation plays an important role in climate resilience, it should not be used to offset emissions in other sectors. Ocean-based sequestration risks diluting mitigation ambition, lacks permanence due to worsening climate impacts, and faces high data uncertainty in measuring carbon flows.
Nusantara, the new capital
The development of Indonesia’s new capital (Nusantara) in East Kalimantan, intended to shift the nation's political centre from Java, has triggered widespread environmental and social concerns. Between 2018 and 2021, the project led to the loss of over 18,000 hectares of forest (Forest Watch Indonesia, 2024), threatening local biodiversity and displacing Indigenous Dayak communities (Modern Diplomacy, 2024; Tempo, 2024). While the government promotes Nusantara as a “green” and “smart forest city”, ongoing deforestation, land reclassification, and exclusionary planning practices highlight the disconnect between official sustainability aspirations and on-the-ground realities (CNN Indonesia, 2024; East Asia Forum, 2024; NASA Earth Observatory, 2024).
Under President Prabowo, the project has not been abandoned, but appears to be deprioritised. Presidential Regulation No. 79/2025 sets a target for Nusantara to become Indonesia’s “political capital” by 2028 (IKN Authority, 2025). However, a 2026 Constitutional Court ruling confirmed that Jakarta remains the capital until the president issues a formal decree transferring the status to Nusantara, keeping the project in legal and political limbo (Tempo, 2026b; The Jakarta Post, 2026d). State funding and private investment have also fallen short of expectations, contributing to growing perceptions of Nusantara as a “neglected” mega-project (The Guardian, 2025).
Agriculture
Agriculture remains a backbone of Indonesia’s economy, employing 30% of the workforce (World Bank Group, 2025). In 2022, the sector accounted for 11% of national GHG emissions (excluding LULUCF), primarily from rice cultivation (40%), enteric fermentation (20%), and the rest from livestock manure and synthetic fertilisers (FAO, 2024; Gütschow et al., 2024). The 2021 LTS-LCCR and 2035 NDC outline mitigation measures such as low-emission rice varieties, alternate wetting and drying, organic fertilisers, improved livestock feed, and biogas production from manure.
Indonesia’s agricultural agenda under the 2025–2029 National Medium-Term Development Plan (RPJMN) is driven by food security, self-sufficiency and increased productivity, while also linking the sector to green economy and net zero objectives. In practice, however, key policies continue to rely heavily on large-scale land expansion through food estates as well as fertiliser and seed subsidy programmes.
The government also envisages a role for agriculture in carbon markets: Presidential Regulation No. 110/2025 extends the carbon economic value framework to agricultural subsectors such as rice farming, livestock and plantations, while the Ministry of Agriculture is preparing implementing regulations and roadmaps for low-emission agriculture (ANTARA News, 2026b; Indonesian Ministry of Agriculture, 2026). The stated aim is to reduce agricultural emissions by 10 MtCO₂e by 2030, but the framework remains at an early stage, and implementation challenges remain.
The food estate programme has been promoted as part of the National Strategic Projects to strengthen food self-sufficiency (Indonesia’s Ministry of Environment and Forestry, 2020), but it has consistently failed to improve national food security despite large budgets, while creating long-lasting social, economic and environmental impacts (CIPS, 2025). Under the current administration, this approach is expected to continue, with around 3 million ha of additional land potentially cleared, including in Central and South Kalimantan, South Sumatra and South Papua (CIPS, 2026).
Many sites are located on peatlands, forests or customary territories, raising risks of deforestation, biodiversity loss, and Indigenous land conflicts (Mongabay, 2024). This agenda can only be compatible with Indonesia's decarbonisation commitments if production gains come from improved efficiency and integrated land management rather than from expanding cultivated area.
These initiatives also neglect more structural food system issues like food distribution inefficiencies and limited access to affordable, nutritious food. More than 20% of children under five are stunted, and nearly 70% of Indonesians cannot afford a balanced diet (CIPS, 2023a). Price disparities in remote regions stem from post-harvest losses, high logistics costs, poor infrastructure, and limited cold chain capacity (WRI Indonesia, 2021). Many food estates are hindered by unsuitable soils, inadequate planning, and disregard for scientific and local knowledge (The Jakarta Post, 2022; Mongabay, 2023).
To improve food resilience while aligning with climate goals, Indonesia should shift toward sustainable intensification, diversify nutritious crop production, invest in rural infrastructure and cold chains, and strengthen agricultural extension services. Redirecting fertiliser subsidies to direct farmer support and improving social registry data would increase targeting efficiency (CIPS, 2023b). Turning agricultural waste into biochar also offers promise as a soil fertility enhancer, long-term carbon sink, and renewable energy source (Setyawan et al., 2024).
Buildings
Indonesia’s building sector is becoming increasingly important for mitigation as urbanisation and electricity demand continue to rise. The sector accounted for around 4% of Indonesia’s CO₂ emissions in 2023 and around 17% of final energy consumption in 2024, but progress on energy efficiency, electrification and green building uptake remains limited (IESR, 2025a). In 2022, MEMR published a roadmap for energy-efficient, low-carbon buildings, with short-term priorities including the enforcement of building codes, appliance efficiency standards, and promotion of net zero energy buildings (MEMR, 2022).
Regulatory efforts on building energy management have had limited impact so far. Government Regulation No. 33/2023 mandates that buildings that consume over 500 TOE or have annual energy bills exceeding IDR 500 million must implement energy management. This is operationalised by MEMR Regulation No. 8/2025, which sets building sector requirements for certified energy managers, regular audits, implementation of energy efficiency programs, and annual reporting. However, compliance remains extremely low: only 4.4% of eligible commercial buildings and 1.2% of government buildings have reported through MEMR’s online energy management portal (IESR, 2025a). Implementation remains constrained by low awareness and lack of enforcement (Indonesian Ministry of Public Works and Housing, 2024).
Electrification also remains limited, particularly for cooking. In 2024, LPG accounted for almost 90% of household cooking energy use, while electric stoves accounted for less than 0.5% (BPS, 2026). If adoption follows historical trends, only around one million households are projected to use induction stoves by 2060, far below the government’s target of 43.4 million (IESR, 2025a). MEMR’s proposed electric stove programme from 2027 could reduce LPG import dependence and recurring subsidy costs, but uptake will depend on targeted support for eligible households and affordable electricity tariffs (ANTARA News, 2026e; IEEFA, 2026d).
Weak appliance standards delay major energy and emissions savings. Indonesia’s minimum energy performance standards (MEPS) for air conditioners remain below ASEAN benchmarks, allowing low-efficiency products to remain in the market (IESR, 2025a). Strict enforcement of the standards, import restrictions on inefficient products, and better inter-ministerial coordination are needed to prevent Indonesia from becoming a market for outdated appliances as cooling demand rises.
Green building certification is off track. MPWH Regulation No. 21/2021 mandates green building certification (BGH) for new and existing large public and commercial buildings, while voluntary certifications such as EDGE (Excellence in Design for Greater Efficiencies) continue to dominate private-sector uptake. The Green Building Roadmap targets around 110 million m² of mandatory certified building area by 2030, but total certified area across mandatory and voluntary schemes reached only around 7.5 million m² in 2024 (IESR, 2025a). Uptake is constrained by limited local government capacity and the absence of incentive regulations.
F uture electricity demand in the building sector will also be shaped by data centres. Indonesia is ASEAN’s third-largest market with operational capacity concentrated in Greater Jakarta and Batam. The RUPTL 2025–2034 acknowledged the rising electricity demand from data centres, but this demand is expected to be met largely by coal and fossil gas generation. Without intervention, power consumption is projected to quadruple to 26 TWh by 2030, with emissions surging to 19 MtCO₂e (Ember, 2025b). Indonesia will need stronger renewable energy procurement options, green data centre standards, as well as power usage effectiveness (PUE) and water usage effectiveness (WUE) requirements, to attract sustainable digital investment while avoiding additional fossil-based electricity demand.
Waste
The waste sector accounts for around 13% of national emissions (excluding LULUCF) and more than 50% of methane emissions as of 2024 (Gütschow et al., 2025). Rapid urbanisation and continued reliance on open dumping have led to a fifteen-fold increase in emissions since 1990. In response, Indonesia has introduced several mitigation strategies, including the National Waste Management Strategy, which targets a 30% reduction in waste generation and 70% treatment by 2025.
The 2022 Enhanced NDC includes a ~20% reduction below 2030 BAU (more than 200% above the 2010 baseline). The 2035 NDC sets an ambitious “zero waste by 2040” and zero emissions by 2050 target, aiming for landfill mining from 2025, zero open burning by 2030, circular economy implementation, no new landfills after 2030, and complete landfill closure by 2040 through waste-to-energy and recycling measures.
Implementation remains far behind these targets. Indonesia’s current waste management rate is only around 24%, with the government targeting at least 53% in 2026 (ANTARA News, 2026c). The waste management system remains largely a linear model, relying on collection, transport and disposal, while many landfills are projected to reach or exceed capacity by 2030 (The Jakarta Post, 2025g). In addition, 48% of households are burning their waste, despite the practice being prohibited, causing harmful air pollution and releasing black carbon (The Jakarta Post, 2024b).
At the subnational level, Jakarta has introduced mandatory household waste sorting and a roadmap to phase down open dumping to address overcapacity at Bantargebang landfill (Tempo, 2026c; The Jakarta Post, 2026l). This is a promising development given Jakarta’s waste problem is driven not only by limited landfill capacity, but also by weak source separation, especially for organic waste, which makes up almost half of the city’s waste. The policy could support methane reduction and improve the recycling rate, but only if it is matched with proper infrastructure and public awareness campaigns.
At the national level, the most significant recent development is the renewed push for waste-to-energy (WtE) backed by Indonesia’s sovereign wealth fund Danantara. Danantara established Denera in April 2026 to coordinate national WtE implementation, with a broader plan to develop 33 plants nationwide. The first batch of WtE projects in Bekasi, Greater Bogor and Greater Denpasar has been designated as National Strategic Projects (The Jakarta Post, 2026e, 2026g).
WtE may help reduce landfill volumes and generate electricity, but it remains a contested solution because it could reinforce a disposal-based model rather than prioritising prevention measures. Indonesia’s wet, organic-heavy waste stream may also raise operational costs, and waste incineration plants could create harmful air pollution, threatening public health (Tempo, 2026d). WtE should be limited to residual waste, with strict emission standards and safeguards for informal waste workers.
The2019 Extended Producer Responsibility (EPR) regulation requires producers, particularly in the food and beverage and retail sectors, to reduce packaging waste by 30% by 2029. Nonetheless, implementation has been weak due to limited enforcement and unclear recycling infrastructure. Meanwhile, the 2022 launch of the National Waste Management Information System (SIPSN) marks a step forward in transparency, though uptake by local governments remains partial.
Mitigation efforts span multiple waste streams (Government of Indonesia, 2024). For solid waste: landfill gas recovery, composting, paper recycling, and the production of refuse derived fuel (RDF) or solid recovered fuel (SRF) for industrial use. Organic waste is increasingly processed using black soldier fly larvae as a low-emission feedstock. In liquid and industrial waste, efforts focus on communal and centralised wastewater treatment (IPAL), biodigesters with methane capture, and sludge utilisation in sectors like palm oil and pulp.
Closing this gap requires a strategic shift from downstream fixes to upstream prevention and systemic reform. EPR enforcement must be matched with targeted investment in waste separation and recycling infrastructure, especially in urban areas. Fiscal transfers and matching grants should support subnational efforts to upgrade landfills and close open dumps. A national wastewater strategy is also needed to scale IPAL coverage and mandate biogas recovery. Finally, integrating informal waste workers into formal systems through cooperatives or waste banks can raise recycling rates and improve livelihoods.
Methane
Indonesia is one of the world’s top six methane emitters, with methane contributing around 22% of its national emissions, excluding LULUCF (Global Methane Initiative, 2025; Gütschow et al., 2025). In 2024, more than half of methane emissions came from waste, around 36% from agriculture, 8% from energy, and the rest from industrial processes (Gütschow et al., 2025). Although the energy sector accounts for a relatively small share, coal mine methane is the fastest-growing source within the sector, driven by Indonesia’s expanding coal production as the third-largest coal producer and the largest thermal coal exporter globally (IEA, 2023a). Independent satellite and mine-level estimates suggest that Indonesia’s coal mine methane emissions could be underreported by a factor of six to seven (Ember, 2024b).
Indonesia joined the Global Methane Pledge at COP26 in 2021, committing to contribute to the global goal of reducing methane emissions by 30% by 2030 from 2020 levels (IEA, 2025b). A recent CAT analysis shows that, to align with the Global Methane Pledge, Indonesia would need to reduce methane emissions by 17% below 2020 levels by 2030.
However, Indonesia has yet to develop a comprehensive methane reduction strategy. Its 2022 Enhanced NDC only addresses methane mitigation in the waste and agriculture sectors, while the 2035 NDC adds energy sector measures, including flaring and venting reduction in upstream oil and gas and fugitive emissions reduction from mineral and coal mining (IESR, 2026d). Existing energy sector policies address methane mostly indirectly through general GHG inventory rules, flare gas management and coal bed methane regulation rather than targeted methane abatement, leaving a policy and data gap that risks undermining Indonesia’s methane reduction commitment (IESR, 2026d).
In May 2026, Indonesia launched the ASEAN-Korea Cooperation for Methane Mitigation (AKCMM), a three-year USD 20m programme funded by South Korea through the ASEAN-Korea Cooperation Fund (GGGI, 2026). The project focuses on reducing landfill methane from organic waste, which makes up more than 60% of waste sent to final disposal sites, by strengthening policy, emissions monitoring systems, bankable waste management projects, and regional dialogue (ANTARA News, 2026d; The Jakarta Post, 2026j).
In the oil and gas sector, Pertamina has begun measuring methane emissions at selected upstream fields in cooperation with Japan’s Organization for Metals and Energy Security (JOGMEC) (The Jakarta Post, 2024a). These are useful steps, but they remain fragmented and project-based, and do not yet amount to a coordinated methane reduction strategy, particularly for coal mine methane (IESR, 2026d).
Indonesia must urgently improve its methane monitoring, reporting, and verification (MRV) systems (IESR, 2024). This includes disaggregating data to the mine and regional levels, mandating public methane emissions reporting and mitigation strategies for mining companies, and including underground coal mines in the national inventory (Ember, 2024b, 2024a). Most importantly, it will require limiting further coal mine expansion and heading towards a just energy transition.
Carbon pricing and Article 6
Indonesia is actively pursuing carbon credit mechanism under Article 6 of the Paris Agreement by strengthening the legal and institutional framework for carbon market operationalisation. The Government of Indonesia has established a supervisory structure and operational guidance through the Financial Services Authority (OJK) to support credible implementation of carbon trading. As highlighted in its 2035 NDC, Presidential Regulation No. 110/2025, replacing Presidential Regulation No. 98/2021, updates Indonesia’s carbon economic value framework and provides a clearer legal basis for carbon market implementation. However, it also reinforces Indonesia’s efforts to enable international credit exports, raising concerns that carbon pricing may be used more to generate revenue than to drive domestic emissions reductions (Media Indonesia, 2025; Tempo, 2025c, 2025a).
Indonesia is positioning itself as a major Article 6 credit seller. It has advanced cooperation with Norway through GGGI, signed an MoU with Singapore to work towards an Article 6 implementation agreement, and expanded recognition of international crediting standards (GGGI, 2025; Reuters, 2025a; MTI Singapore, 2026).
This presents several risks: first, Indonesia may be incentivised to keep its NDC ambition low enough to create “excess” reductions for sale, contrary to Article 6’s aim of raising ambition and ensuring environmental integrity. Second, Indonesia risks selling its “low-hanging fruit” reductions, particularly from the LULUCF sector, which could leave the country with fewer and more costly abatement options. Finally, internationally transferred mitigation outcomes (ITMO) revenues should not be counted as climate finance, which is an obligation for developed countries under Article 9, since corresponding adjustments make the seller country’s own target harder to achieve.
Domestic carbon pricing still sends a weak signal. The compliance carbon market, facilitated by the Indonesia Stock Exchange (IDX) through IDXCarbon, has shown limited progress (IEEFA, 2025d). Indonesia applies a hybrid carbon pricing system for its power sector combining cap-and-trade and a fallback carbon tax, but the current scheme still has lenient caps that create little incentive to trade or reduce emissions. Indonesia expanded its emissions trading scheme (ETS) in 2025 to cover captive coal and fossil gas plants and is preparing to expand the ETS to industrial sectors such as cement and fertilisers (ICAP, 2026). However, allowance allocation was postponed, and the proposed carbon tax of IDR 30,000/tCO₂e (USD2/tCO₂e) remains unenforced due to gaps in measurement, reporting, and verification (MRV) and industry resistance (IEEFA, 2025d).
The EU’s Carbon Border Adjustment Mechanism (CBAM) adds further pressure. Since the EU CBAM definitive regime began in January 2026, Indonesian exporters of covered goods such as cement, iron and steel, aluminium and fertilisers face stronger pressure to report embedded emissions and demonstrate whether a domestic carbon price has already been paid. Indonesia’s low carbon price and slow industrial decarbonisation could create a carbon price gap and a competitiveness risk.
Further analysis
Country-related publications
Stay informed
Subscribe to our newsletter