
Viet Nam
Policies & action
Viet Nam’s current policies and action are rated as “Critically insufficient” when compared to its fair share contribution. The “Critically insufficient” rating indicates that Viet Nam’s policies and action in 2030 reflect minimal to no action and are not at all consistent with the 1.5°C temperature limit. If all countries were to follow Viet Nam’s approach, warming would exceed 4°C.
Viet Nam’s emissions under current policies will reach around 673–675 MtCO2e in 2030 (excl. LULUCF) whereas a 1.5˚C fair share pathway is 344 MtCO2e in 2030.
Further information on how the CAT rates countries (compared to modelled domestic pathways and fair share) can be found here.
Policy overview
The CAT estimates that Viet Nam's emissions, excluding LULUCF, will range from 673–675 MtCO2e in 2030 under current policies. This estimate reflects a reduction compared to our last assessment (in GWP AR5 emissions under current policy was 686–722 MtCO2e), mainly due to the downward adjustment made to the growth rate of other CO2 emissions during 2026–2030. We updated this to be consistent with the IMF’s projection of Viet Nam’s GDP growth rate for the same period.
Although Viet Nam has adopted several cross-sectoral policies in recent years, emissions under current policy projections (CPPs) are increasing in 2030, reaching a level 23% higher than in 2025. To be aligned with its fair share contribution, the emissions in 2030 need to be around half of what it would be under current policies. This is because, aside from the updated PDP8, most newly announced or adopted policies are at the framework-level or await detailed implementing regulations and quantifiable parameters; therefore, they are not yet included in our CPPs.
The architecture of Viet Nam’s climate action framework to 2050 is articulated in the National Climate Change Strategy to 2050, setting the goal of reaching net zero by 2050. Viet Nam’s new Electricity Law (2024), which came into effect on 1 February 2025, marks a significant reform of the country’s energy sector. It replaces the earlier framework from 2004 (and subsequent amendments) with a much more comprehensive and ambitious legal foundation. The law sets out detailed provisions on electricity planning, project development, licensing, market competition, grid operations, pricing, and state oversight.
However, the law’s effectiveness will heavily depend on the speed and clarity of implementing regulations, particularly those affecting renewable energy incentives, emergency project management, and pricing frameworks.
Over the short term to 2030, the 14th Party Congress, held in January 2026, set targets to reduce energy intensity per unit of GDP by 1–1.5% annually and GHG emissions by 8–9% during 2026–2030 (reference year or baseline unclear) (Viet Nam Government News 2026a). However, Resolution 70, which updates Resolution 55 and sets Viet Nam’s overarching energy strategy and direction, marks a deviation from the country’s long-term decarbonisation goal. It places greater emphasis on energy security and short-term economic growth, while endorsing a continued role for fossil fuels in the energy system through 2030. This was largely driven by the energy crisis triggered by the closing of the Strait of Hormuz.
In December 2025 came Resolution 253, aimed at supporting the implementation of 2025 Power Development Plan (2025 PDP8) by addressing the bottlenecks in power planning, grid infrastructure and offshore wind development, also provides special mechanisms for continued fossil fuel projects.
Following this, Viet Nam’s National Energy Master Plan for 2021–2030, a foundational framework for energy-sector decarbonisation, was revised in February 2026 and now includes continued support for coal. These shifts create significant uncertainty for Viet Nam’s energy transition and decarbonisation trajectory. They also sit uneasily with the country’s 2050 coal phase-out target under the 2025 PDP8 and its commitment under the Just Energy Transition Partnership (JETP) to limit coal-fired power expansion.
Recent policy developments therefore send mixed signals. On the one hand, the government has adopted measures to address barriers to renewable energy scale-up, including increased grid investment, accelerated solar deployment and a legal framework for offshore wind development. On the other hand, it continues to endorse fossil fuels in the energy system. This risks diverting resources away from renewables and grid investment, creating long-term carbon lock-in and increased energy security risk due to increased reliance on fossil import.
As part of the strategy in response to energy security concerns, Viet Nam is also accelerating nuclear development. It has already established international cooperation with Russia and adopted a nuclear development strategy with targets for 2035 and 2050. While nuclear energy does not emit CO2, its high operating costs, high nuclear accident, security and proliferation risks, and lengthy construction period makes it an inferior decarbonisation option when compared to much cheaper wind and solar.
In the transport sector Decision No. 1679/QD-BGTVT signifies a crucial step towards the integration of green energy measures in the transport sector, marking a significant move towards the execution of the Prime Minister's Action Programme on green energy transition and the reduction of carbon dioxide and methane emissions in transport (Decision 876/QĐ-TTg), steering the sector toward net-zero by 2050. It has the largest EV market in south-east Asia and would see continual growth supported by the new 2026 measures, which aim to expand charging infrastructure in apartment buildings and urban area (IEA 2026c; LuatVietnam 2022; VietnamPlus 2026). In 2026, it has operationalised its long-delayed E10 biofuel blending roadmap and mandated the nationwide use of E10 biofuel to start from June 2026 (Viet Nam Government 2026c).
In the buildings sector, energy efficiency has been strengthened by the 2023–24 amendment to the Law on Energy Efficiency and Conservation. This expanded mandatory labelling and minimum performance standards to include construction materials, while introducing stronger requirements for energy audits, monitoring, and financing mechanisms.
Agriculture, a major source of methane emissions in the country, has also undergone a policy shift. The 2022 Methane Emissions Reduction Action Plan set quantified limits on emissions from cultivation and livestock. A Low-Emission Crop Production Plan launched in 2023 targets a 30% cut in methane from crops and a 10% cut in overall agricultural emissions by 2030 from 2020 level.
The waste sector has seen particularly notable reform. The 2022 Environmental Protection Law introduced mandatory waste sorting and extended producer responsibility (EPR). In early 2025, the government approved a National Action Plan for Implementing the Circular Economy until 2035, setting a long-term vision for reducing waste, increasing reuse and recycling, and improving resource efficiency across all sectors.
Resolution 70-NQ/TW
Addressing shortcomings identified in the implementation of the previous Resolution 55, Viet Nam adopted Resolution 70-NQ/TW in August 2025, setting the country’s overarching energy policy direction and objectives to 2030, with a vision to 2045.(thuvienphapluat.vn 2025) The Resolution places greater emphasis on national energy security and supporting rapid economic growth. While it strengthens some elements of the renewable energy framework, it also reinforces the role of fossil fuels in maintaining energy security, weakening the direction of the energy transition.
Resolution 70 calls for a gradual reduction in the share of coal-fired power but does not set a coal phase-out date. At the same time, it calls for maintaining stable coal supplies and reserves for power generation, upgrading the technology and efficiency of existing coal plants, and establishing mechanisms to encourage their conversion to gas, bioenergy, hydrogen and ammonia.
This weakens the direction set out in the revised 2025 Power Development Plan (PDP8), which envisages phasing out unabated coal-fired generation by 2050, and contradicts Viet Nam’s commitment to cease coal-fired generation expansion under the Just Energy Transition Partnership (JETP).
Resolution 70 also promotes LNG imports as part of ensuring energy supply, reinforcing the continued expansion of LNG infrastructure. Such expansion increases import dependence and exposure to volatile international LNG markets, posing significant risks to national energy security and potentially undermining the Resolution’s own energy security objectives, while also creating the risk of long-term fossil gas lock-in.
Despite these shortcomings, Resolution 70 strengthens several elements of the policy framework needed to address existing barriers to renewable energy deployment compared with Resolution 55. It calls for support mechanisms for rooftop solar, energy storage and offshore wind, alongside the development of a renewable energy certificate market and further electricity-market reform. It also strengthens several economy-wide energy targets. By 2030, renewables are targeted to account for 25–30% of total primary energy supply, up from 15–20% under Resolution 55.
The Resolution also targets a 15–35% reduction in energy-related GHG emissions relative to the business-as-usual (BAU) scenario and 8–10% final energy savings relative to BAU by 2030. For the power sector, Resolution 70 largely reiterates the targets already established in the revised 2025 PDP, including the 2030 electricity generation target of around 560–624 TWh, and the 2030 installed generation capacity target of around 183–236 GW (Viet Nam Government News 2025). It also expects a potential higher growth of capacity due to the increase in electricity demand and socio-economic development.
2026 Update of Master Plan on National Energy (2021–2030)
In February 2026, Viet Nam revised its National Energy Master Plan (2021–2030) to align energy planning with the country's higher economic growth expectations, Resolution 70 and the 2025 PDP8. The revision substantially raises projected energy demand to 120–130 Mtoe by 2030 and strengthens the role of renewables, increasing the 2030 renewable energy objective from 15–20% to 25–30% of primary energy supply and incorporating stronger energy-efficiency objectives (HuongCNT 2023; thuvienphapluat.vn 2026a).
However, the plan continues to envisage substantial coal production and gas/LNG infrastructure development. So while the revision accelerates renewable energy deployment, it does not establish a correspondingly stronger fossil-fuel phase-out pathway.
Market mechanism: Domestic carbon market and international transfer
Viet Nam is undertaking a significant step in its climate policy with the launch of a pilot emissions trading scheme (ETS) in August 2025. This development builds on earlier legislation (Decree 06/2022/ND-CP), which introduced emissions reporting obligations—and was formalised through Decision 232/QD-TTg in January 2025, followed by Decree 119/2025/ND-CP in June (Viet Nam Government 2025b). Together, these measures create the legal framework for Viet Nam’s first emissions trading scheme, which is central to its strategy for meeting its Nationally Determined Contribution and long-term net-zero by 2050 target.
The pilot ETS will initially cover the thermal power, cement, and iron and steel industries, sectors that together account for about half of Viet Nam’s total CO2 emissions (Enerdata 2025). During the trial phase, companies will receive allowances free of charge, allocated according to production-based emissions intensity benchmarks (ICAP 2025). Importantly, firms will also be able to use carbon credits from domestic or international markets to offset up to 30% of their emissions obligations—a more generous threshold than earlier proposals, which limited offsets to 10–20% (S&P Global 2025).
While the pilot marks an important milestone, it also highlights the complexity of designing a functioning emissions trading scheme. A national registry for tracking allowances is being developed, along with a trading platform to facilitate transactions, but these systems are not yet fully operational. Moreover, oversight will involve multiple ministries, raising concerns about coordination and consistency in enforcement (Reccessary 2025b).
Moreover, the market is based on intensity-based benchmarks and that could limit the scheme’s effectiveness (Reccessary 2025b). If production in covered sectors continues to expand, companies may reduce emissions per unit of output while still increasing their total emissions. In addition, the decision to allocate most allowances for free means that the market may initially deliver limited short-term emissions cuts, with the emphasis instead on building institutional capacity and familiarising firms with trading mechanisms (Reuters 2025b).
The success of the pilot will therefore be critical: if it is able to establish robust institutions, improve data quality, and generate confidence among participants, it could evolve into a well-functioning instrument for Viet Nam’s low-carbon transition. If not, the risk is that it remains more of a capacity-building exercise than a driver of deep decarbonisation.
Large facilities in cement, steel, and ceramics are now required to prepare greenhouse gas inventories. These inventories serve as the foundation for Vietnam’s first emissions trading scheme.
In 2026, the government approved the first allowance allocations for 2025–2026, covering thermal power, steel and cement; established registry, trading, custody and settlement rules; and created a framework for international carbon credit transfers under Article 6 (LuatVietnam 2026; Viet Nam Government 2026g, 2026a). Decision 263/QĐ-TTg sets Viet Nam’s total pilot GHG emission quota at 243.08 MtCO2e in 2025 and 268.39 MtCO2e in 2026, an increase of around 10.4%, suggesting that the pilot aims to build market and compliance readiness rather than impose an immediate emissions reduction obligation (International Climate Initiative (IKI) 2026; Viet Nam Government 2026f).
In September 2025, Viet Nam signed a bilateral agreement with Singapore, which enables Viet Nam to authorise mitigation outcomes for transfer to Singapore with corresponding adjustments to prevent double counting while implementing Article 6 (Singapore’s Carbon Markets Cooperation 2026; Viet Nam Government 2026h).
To prevent double counting of internationally transferred mitigation outcomes, Decree 112/2026/NĐ-CP requires Article 6 ITMOs to undergo a corresponding adjustment, under which transferred mitigation outcomes are added back to Viet Nam's national emissions accounting and can only be counted towards the NDC or other mitigation objective of the receiving party (thuvienphapluat.vn 2026b).
Power Sector
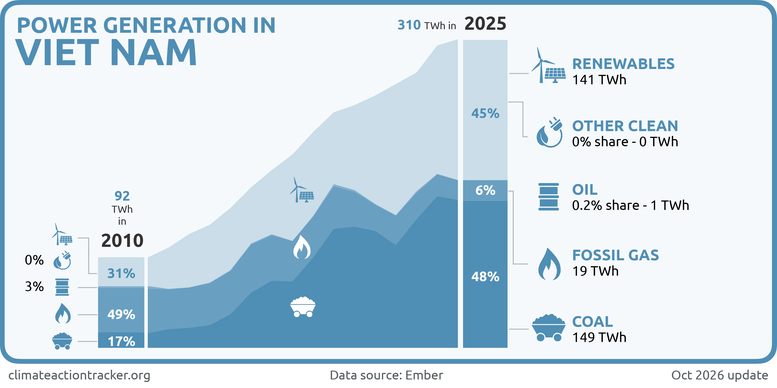
Viet Nam's power sector is a significant contributor to the country's total emissions, accounting for approximately 50% of total energy related emissions in 2024 (IEA 2026d). This is driven largely by the reliance on fossil fuels, particularly coal, which accounts for nearly 48% of total generation in 2025 and 90% of sectoral emissions (Ember, 2026).
In recent years, electricity demand has been rising sharply, reflecting rapid industrialization and urbanisation. Large hydro plays important role in the electricity mix, with around 31% of electricity generation in 2025 (Ember, 2026). However, there is significant uncertainty in hydro generation in recent times due to drought. While electricity generation from solar and wind are gradually increasing, they still only account for a smaller share of 15% in 2025 (Ember, 2026).
Considering historical trends and official targets, alongside current policies and government plans for the energy sector, we evaluate Viet Nam’s power sector as:
- Moving in the “Wrong direction” on coal,
- Moving in the “Wrong direction” on fossil gas, and
- Making “Slow progress” on renewables.
Power Development Plan 8 (PDP8)
The 2025 update of Power Development Plan 8 (PDP8) is designed with an annual GDP growth aligned with historical expansion of around 10% between 2026–2030 and 6.5–7.5% between 2031–2050, which would see commercial electricity consumption alone to increase by 74–94% by 2030 compared to 2025 levels reaching 500.4–557.8 bn kWh by 2030 (moit.gov.vn 2026).
The revised PDP8 sets emissions from electricity generation at 197–199 MtCO2e by 2030, while reaffirming the same 170 MtCO2e peak under JETP. It targets slightly lower near-term shares of renewables but set more ambitious long-term goals: up to 295 GW of solar, 139 GW of offshore wind, and 70% renewable capacity by 2050. Nuclear power, cancelled in 2016, has been reintroduced as a strategic option, with up to 14 GW planned by 2050, with a total capacity share of 2%.
PDP8 continues to rely on fossil fuels in 2050, particularly fossil gas and LNG. In the 2025 PDP8, fossil gas, including LNG, is positioned as a strategic replacement, with capacity projected to grow to 33–37 GW by 2030 (16–18% of total installed capacity), though this risks long-term carbon lock-in and energy security vulnerabilities as it will increase its reliance on LNG import.
While the 2025 PDP8 sets a 2050 coal phase-out target, Resolution 70, issued several months after 2025 PDP, set the overarching national energy strategy and allows for sustained coal-fired generation while promoting the continued role of fossil gas in the energy system. Following this strategy, the Resolution 253, which is aimed at supporting the implementation of the 2025 Power Development Plan (2025 PDP8), provides special mechanisms for continued fossil fuel projects, while also addressing the bottlenecks in power planning, grid infrastructure and offshore wind development. This strategy shift reflected in Resolution 70 brings great uncertainty to Viet Nam’s decarbonisation trajectory.
To operationalise the 2025 PDP8, a total of USD 118.2 bn for power generation projects and USD 18.1 bn for transmission grid development is needed (moit.gov.vn 2026). The government should provide a favourable environment that aligns with international financing mechanisms, such as the Just Energy Transition Partnership (JETP), to scale up the domestic and foreign investment.
Just Energy Transition Partnership (JETP)
In December 2022, Viet Nam joined the Just Energy Transition Partnership (JETP). This partnership will provide USD 15.5bn in support until 2026–2028 from a group of donor countries (IPG; now comprised of the EU, the United Kingdom, Canada, Denmark, France, Germany, Italy, Japan, Denmark and Norway, and co-led by the EU and the United Kingdom) to help Viet Nam reach its net zero commitment by 2050. The JETP Resources Mobilisation Plan detailing the conditions of the partnership was released in December 2023 (Government of Viet Nam 2023).
Key elements of the agreement include the peaking of power sector emissions in Viet Nam at 170 MtCO2e in 2030 and a targeted share of 47% of renewables in power generation by 2030 (European Commission 2022). The JETP aims at bringing forward Viet Nam’s peak emissions target from 2035 to 2030. The agreement also includes a biennial revision of the targets.
In March 2026, Viet Nam updated its framework for implementing the JETP through Decision 458/QĐ-TTg, aligning it with the revised PDP8 and Resolution 70. While the Decision retains the 170 MtCO2e cap on peak power-sector emissions, it weakens two key elements of the original JETP: it increased the coal capacity ceiling from 30.2 GW to a range of 30.2–31.055 GW and changed the 47% renewable energy target from a minimum share of electricity generation to an approximate share of installed generation capacity (thuvienphapluat.vn 2026e).
The decision also replaces the JETP's explicit direction towards phasing out unabated coal generation with a framework under which coal plants over 40 years old are retired if they cannot convert to alternative fuels (thuvienphapluat.vn 2026e).
As of July 2026, Viet Nam and its international partners have identified 50 JETP-eligible projects requiring more than USD 11bn in financing, growing from 24 eligible projects identified in July 2025 requiring over USD 7 bn (moit.gov.vn 2026; The Saigon Times 2025). Out of those 50 eligible projects, just three projects have successfully mobilised investments – totalling nearly USD 800m – including the Ho Chi Minh City-Binh Duong power transmission line project (USD 78 million), the Tri An Hydropower Plant expansion project (USD 79 million), and the Bac Ai pumped-storage hydropower project (USD 565 million).
The JETP Secretariat has been placed under the Ministry of Industry and Trade (MoIT), which is responsible for the energy sector, and a five-step project screening process has been introduced to ensure greater transparency in how JETP funds are allocated (European Comission 2025). This is being aligned with Viet Nam’s updated 8th Power Development Plan (PDP8), approved in 2025, so that selected projects fit into the country’s long-term energy strategy.
Despite these advances, challenges remain. Although project pipelines are growing, actual disbursement of funds has been slow—as of September 2026, EUR 13.71 million disbursed for the Bình Dương 1 transmission substation, the first completed JETP project in Viet Nam (EVN.COM.VN 2026). Other major projects continue to face financing and implementation barriers, highlighting the gap between financial commitments and actual investment (Vietnam Investment Review 2026).
The scale of funding is also of concern: while USD 15.5 bn is substantial, Viet Nam’s estimated energy transition costs reach USD 135 bn by 2030, and as much as USD 364–511 bn by 2050 (International Rivers and Vietnam Climate Defenders Coalition 2024). This means JETP resources will cover only a fraction of what is needed. To meet the full financing gap, it will be crucial for Viet Nam to also leverage private capital and domestic resources and increased international climate finance beyond JETP commitments.
In early March 2025, the United States withdrew its JETP funding commitment of over USD 3 bn designated for Indonesia and Viet Nam (largely in the form of commercial loans/guarantees), narrowing the financing envelope (Reccessary 2025a). Given that U.S. disbursements under JETP were limited at the time of withdrawal, immediate project-level disruption appears limited; an delays would stem from re-papering financing packages with remaining partners (Nangoy 2025).
Policy and governance issues further complicate implementation. Viet Nam has made some progress in improving its legal framework for renewables and grid development, but gaps remain in areas such as ODA regulation, planning coherence, and debt management (European Comission 2025). Civil society groups have also raised concerns about whether the process is sufficiently inclusive and transparent, questioning how strongly the “just” element of the transition is being upheld.
Coal
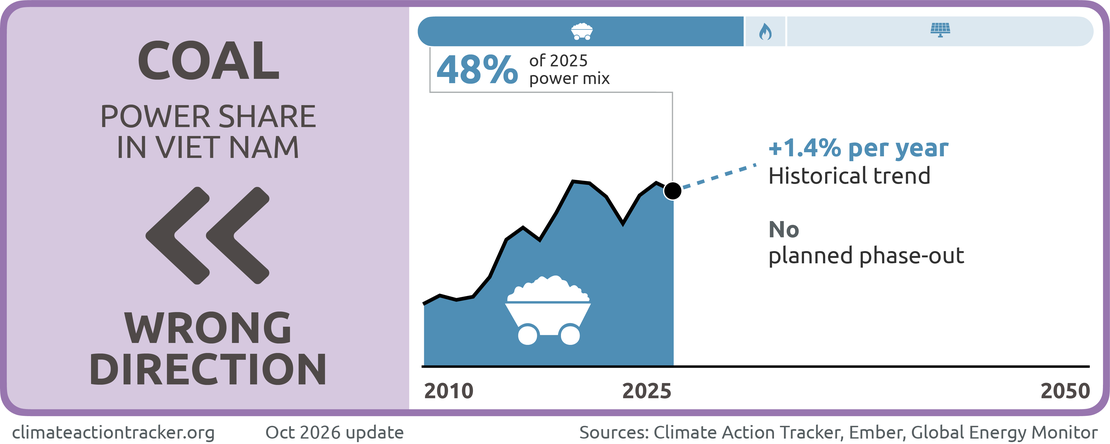
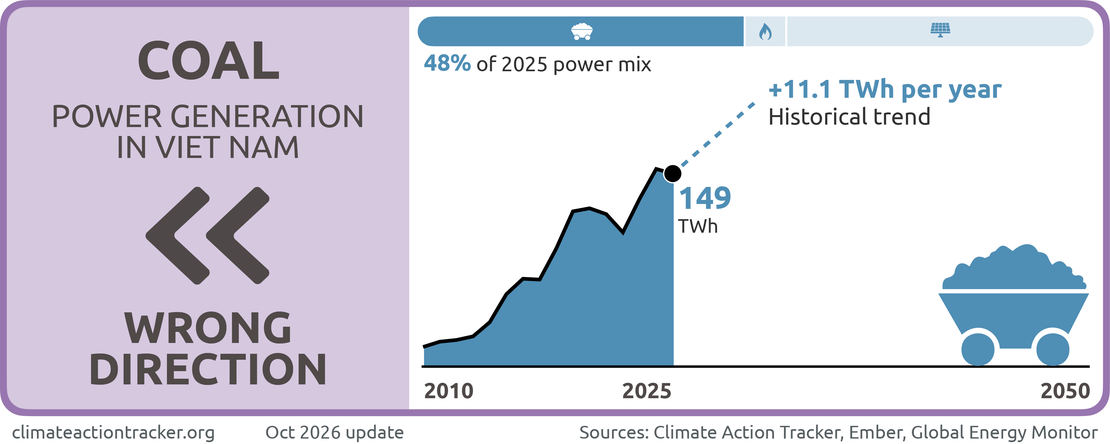
In 2025 coal-fired generation increased to 157 TWh, accounting for nearly 48% of the power mix. While this represents a slight decrease from 49% the year before, coal’s share of total generation has increased sharply over the last decade, from 35% in 2015 and just 17% in 2010 (Ember, 2026). While this upward trajectory may be slowing due to government planning, financial trouble with plant operations, and an accelerating renewables rollout, coal remains the largest source of energy sector emissions in the country (IEA 2026d).
By moving away from previously agreed 2050 coal phase-out, Viet Nam is moving in the wrong direction. The real-world trajectory is not aligned with a fast transition away from coal as it has still increased its coal capacity ceiling in the JETP, if only marginally. Its share in total power generation remains high, coal imports are rising, and in the context of ongoing geopolitical turmoil, reliability concerns are keeping coal central in dispatch. The recent update on the coal has thus seen major weakening of its climate commitments.
As a result, we evaluate Viet Nam as moving in the “Wrong direction” on the role of coal in the power sector.
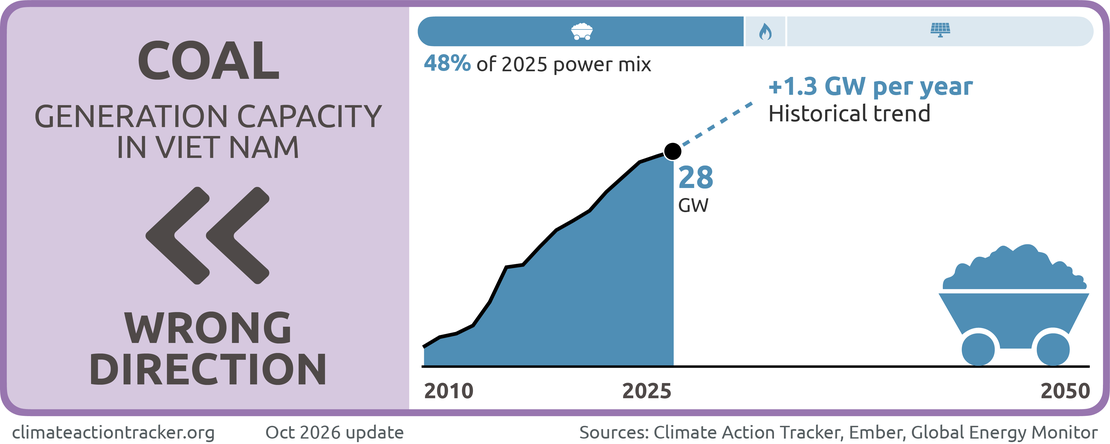
With 27.7 GW of installed capacity in 2025, coal accounts for about 32% of Viet Nam’s capacity mix (Ember, 2026). Coal will keep playing a key role in the country’s power mix, with a capacity target of 31 GW by 2030 in the updated 2025 PDP8. The 2023 PDP8 anticipated a gradual reduction but did not commit explicitly to a complete phase-out.
However, Viet Nam is consistently including operational capacity, recently driven by energy security concern due to the closure of the Strait of Hormuz (Reuters 2026d). As of July 2026, operating coal capacity has already reached around 28.4 GW with another 2.7 GW under-construction installation to be added to the pipeline (Global Energy Monitor 2026). While the aggregate value suggests that Viet Nam should halt any further coal capacity installation, the newly announced 3.2 GW capacity and the additional 1.98 GW currently under permit application risks Viet Nam exceeding its 2030 coal capacity target (Global Energy Monitor 2026).
To curb the continual coal expansion and align with Viet Nam’s net-zero by 2050 pledge, the government should impose stricter control of its growth in coal capacity. Contrary to this, Resolution 70 is now indicating only a reduction in coal use, reflecting a softened stance on complete coal phase-out (thuvienphapluat.vn 2025). This would deepen its reliance on coal, lock in carbon emissions for another decade, and create challenges for Viet Nam’s Just Energy Transition Partnership (JETP) commitments of reaching peak GHG emissions in 2030.
An increasing number of coal projects are already being cancelled in Viet Nam, mainly due to a lack of financial viability, with 60 GW of coal-fired projects shelved between 2010 and 2025 (Global Energy Monitor 2025). However, with around 4 GW of coal-fired plants under construction and around 2 GW still in pre-construction stages as of July 2025, questions remain around Viet Nam’s commitment to phasing out coal by 2050 (Global Energy Monitor 2025).
Coal Supply
Viet Nam mines roughly 43–45 million tonnes of coal annually, but this output falls far short of national consumption, particularly for the power sector, where demand has more than doubled over the past fifteen years (ASEM Connect 2023). Viet Nam therefore is highly reliant on coal imports.
Viet Nam imported a record high of 65.43 m tonnes of coal in 2025 and 32.9 m tonnes in the first five months in 2026 (Argus Media 2026; Reuters 2026b). The surge in imports also complicates Viet Nam’s balance of payments and raises questions about long-term affordability, particularly if coal prices rise again. Government planning documents acknowledge these realities. Imports are projected to increase to 64 Mt in 2026 and keep increasing to 73 Mtpa by 2030, 85 by 2035, before decreasing to 50 Mtpa by 2045 (Do and Burke 2023; IEA 2026a; VietNamNet 2023).
Its energy demand from the industrial expansion along with the energy supply constraint from the Iran War has spurred the government to raise domestic coal miners’ output by up to 15% above the quotas until the end of 2027 (Reuters 2026b).
This reliance on coal—domestic or imported—sits uneasily with Viet Nam’s climate commitments. The country has pledged to reach net zero emissions by 2050, yet its coal consumption is still rising. The Master Plan on National Energy forecasts imports to dramatically drop from 50 Mtpa in 2045 to zero by 2050 (Viet Nam Government 2023). While this is an ambitious goal, albeit too late to respect the Paris Agreement’s goal of limiting global warming under 1.5°C degrees, a complete elimination of coal imports within just five years is overly optimistic and may not be realistically achievable, especially without corresponding changes in the power mix. In contrast, a comprehensive and gradual planning of the transition would offer Viet Nam a more secure path to phasing out coal without jeopardising economic goals.
Fossil gas
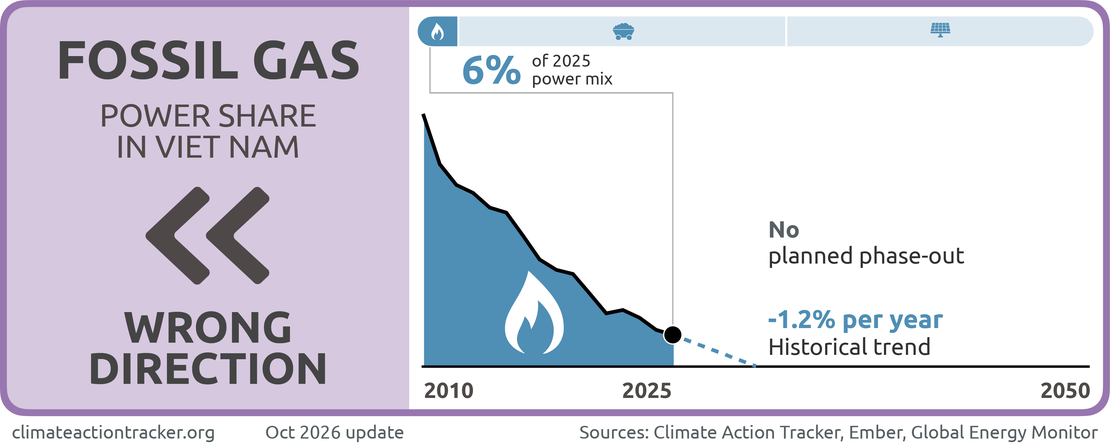
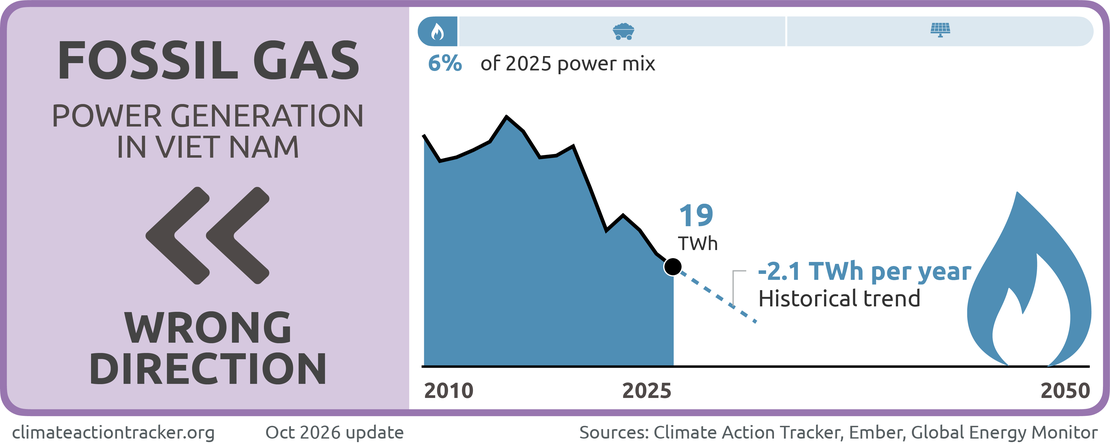
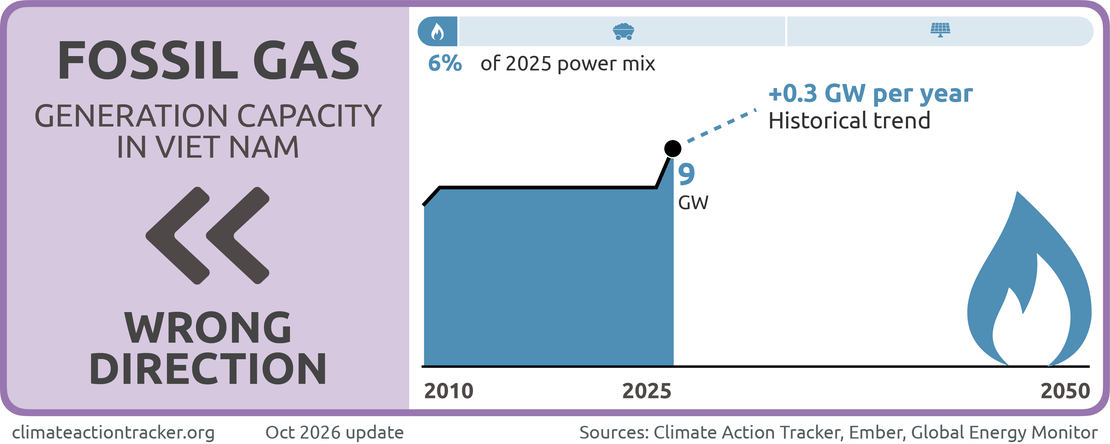
Fossil gas currently plays a minor role in Viet Nam’s energy system, but the planned capacity is increasing. It accounted for about 6% of power generation in 2025 (Ember 2025). Although the share of gas in total power generation and its absolute generation both have declined in past three years, the PDP8 identifies gas and LNG-fired power as a central element of the country’s strategy to secure energy supply while gradually reducing dependence on coal.
Due to sustained government expansion plans and the risks of replacing coal dependence with reliance on imported LNG, increasing exposure to price volatility and external supply shock, we evaluate the role of fossil gas in Viet Nam’s power sector as moving in the “Wrong direction.”
The 2025 PDP8 planned for 33–37 GW gas capacity (including 22.5 GW LNG import) by 2030 and around 45 GW targeted by mid-century, placing stricter caps on LNG imports and prioritising domestic production.
As of 2025 Viet Nam, has more than 11 GW of fossil gas capacity under construction, and of that, 10 GW is through imported LNG. Another 43GW of fossil gas capacity is under different stages of pre-construction phase.
LNG-to-power projects are explicitly eligible for government support under Viet Nam's new Electricity Law 2024, which aims to promote fossil gas-fired power generation, including the use of imported LNG (ho 2025). Viet Nam’s fossil gas generation goals will necessitate fuel imports capacity of 16-18 billion cubic metres per year by 2030 and 11-13 by 2050 (Viet Nam Government 2023).
Viet Nam is planning to increase the domestic production of gas up to 5.4-11 billion cubic metres per year by 2030, 9-15 for 2031-2035 and 14-18.8 for 2036-2050 (thuvienphapluat.vn 2026d). In 2025, the domestic gas production was 5.8 billion cubic metres (Energy Institute 2026).
Several major projects are moving forward. The Nhon Trach 3 and 4 plants, designed to run on imported LNG, are among the first large-scale facilities expected to come online. Other projects, such as the Son My LNG-to-Power complex, the Bac Lieu LNG project, and the Long Son LNG plant, have been announced or are in advanced planning stages. These complement existing gas capacity at the Phú Mỹ power complex (The Asset 2025).
In May 2023, the state-owned company PetroViet Nam (PV) Gas built the first LNG import terminal in the country (Enerdata 2023). The current plans for the development of LNG terminals suggest that their capacity will not be sufficient to meet the demand implied by the PDP8. The new LNG import terminals at Thi Vai and Hai Linh are being developed to account for the country’s growing dependence on imported fuel.
In January 2026, PV Gas signed Viet Nam’s first long-term LNG contract with Shell, which will supply about 400,000 tonnes per year during 2027-2031 (Reuters 2026d). In June, PV Gas signalled a second long-term LNG tender, which will supply 250,000–450,000 tonnes to the Thi Vai Terminal, with delivery expected to start in January 2027 or later (Reuters 2026c). Despite such push, in July 2026, only 7.3% of LNG import target was met, due to regulatory hurdles, lack of investor interest and concerns about LNG supplies due to the closure of the Strait of Hormuz (Reuters 2026d).
Fossil gas is not a transition fuel and hinders progress towards reaching both national and international climate objectives (Climate Analytics 2021). PDP8 further plans that fossil gas plants projects will be transitioned to hydrogen when financial conditions allow it, despite uncertainties regarding the environmental sustainability of the type of hydrogen used (it is unlikely to be renewable).
The massive efforts Viet Nam’s government is directing towards the fossil gas sector development are not at all 1.5°C compatible and raise the spectre of significant stranded asset risks, with a phase-out timeline contingent upon the technological and economic viability of hydrogen as a fuel. Increasing the dependency on imported energy will risk the country's vulnerability to energy security threats in a complex geopolitical landscape.
Renewables
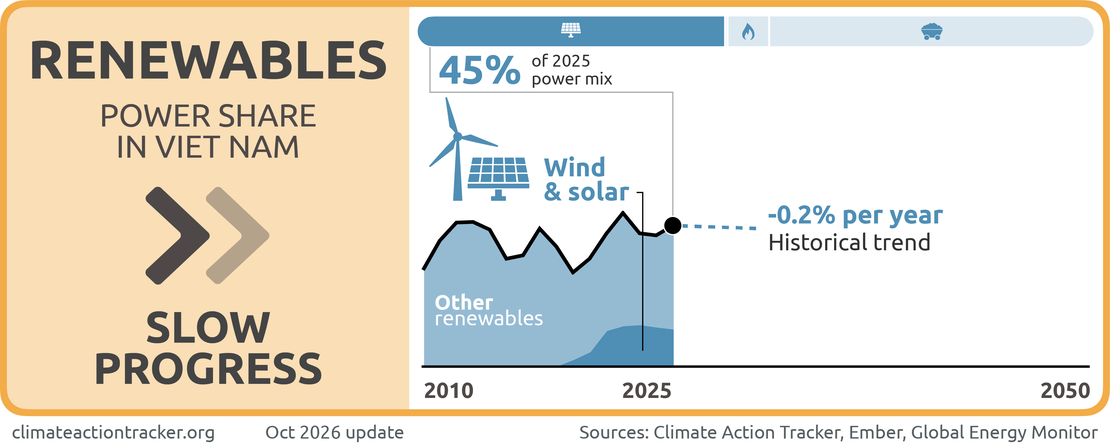
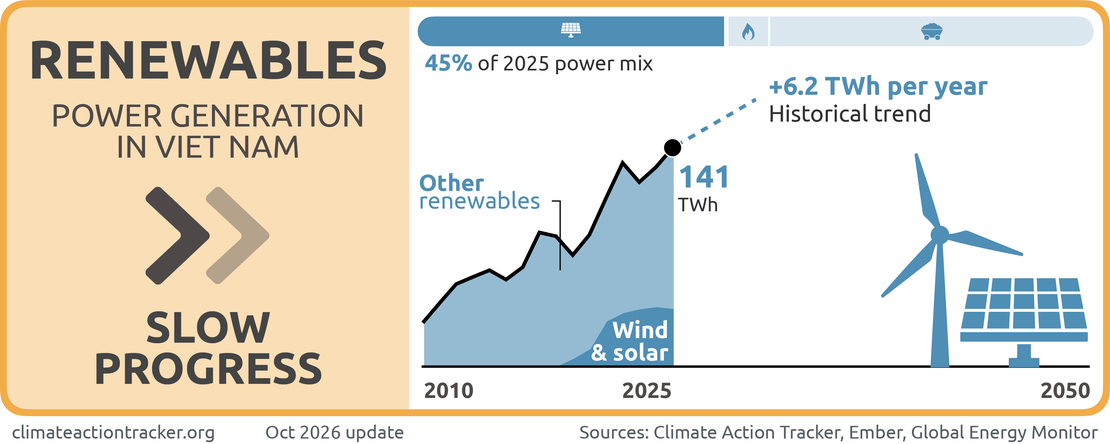
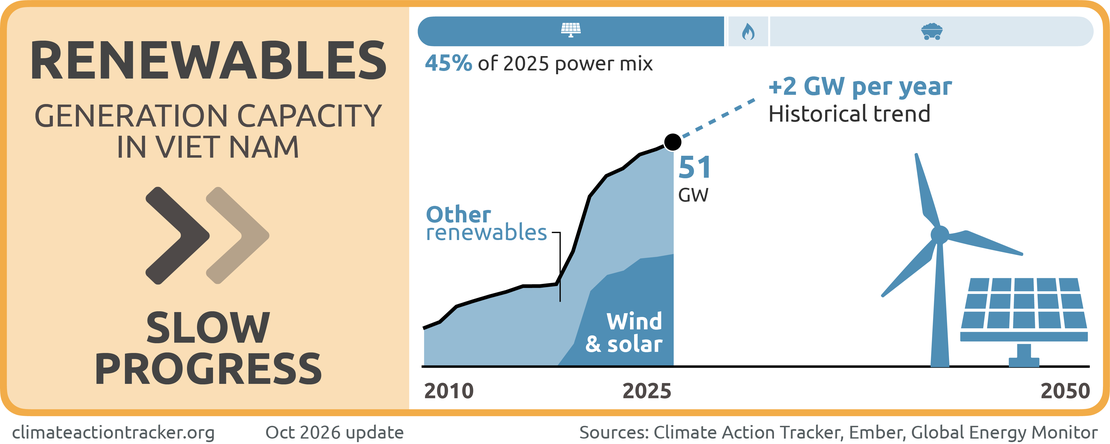
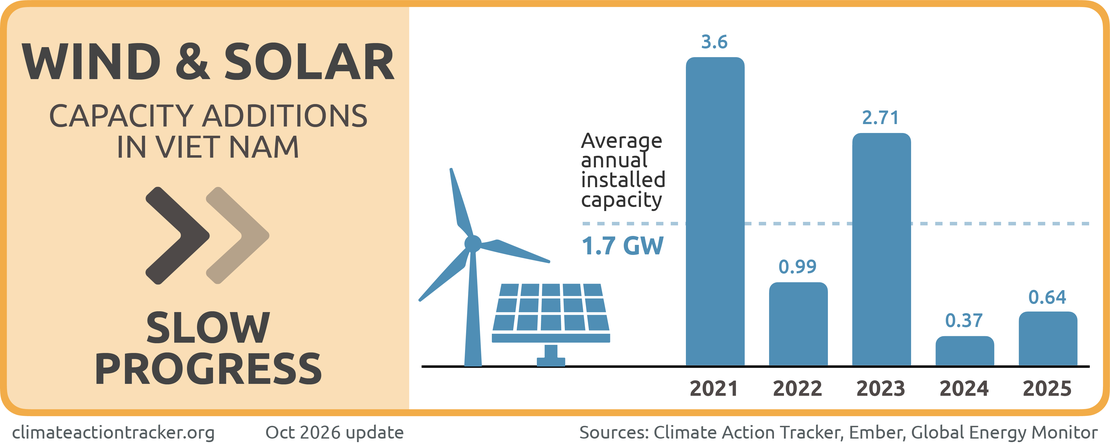
In 2025, renewable energy sources accounted for 45% of electricity production, including hydro (Ember, 2026). Hydroelectricity generated 31% of Viet Nam’s electricity in 2025, a slight decrease compared to 35% in 2015 (Ember, 2026). Wind and solar generation have increased significantly since 2018, when they provided a negligible share of total electricity, reaching 15% in 2025.
The 2025 PDP8 targeted 40–47% renewable capacity share by 2030, and 66–71% by 2050 (excluding large hydro). By 2030, it targets solar to reach 73 GW, wind onshore capacity 26–38 GW, offshore wind could expand to 17 GW. By 2050, it targets solar to reach nearly 300 GW, onshore wind 91 GW, and offshore wind 139 GW. Hydropower, already heavily exploited, will remain stable at around 33–35 GW in 2030 and increase to up to 40 GW in 2050, playing an important role in grid balancing.
In the recent update of JETP Viet Nam has weakened one of the key elements of the original JETP of the renewable energy target, by replacing the at least 47% renewable electricity generation target with a target of 47% renewable installed capacity. Shifting from generation target to capacity target signals the weakening of renewable deployment ambition.
With the revised PDP8 significantly scaling up solar, wind and offshore wind while strengthening grid development to support higher renewable penetration, we evaluate Viet Nam as making “Slow progress” on the role of renewables in the power sector.
Solar deployment has largely stalled since Viet Nam's rapid expansion in 2019–2020, with installed capacity remaining at 19.25 GW in 2025 (Ember 2025) mainly due to grid constraints and limited storage. To address this issue, Viet Nam introduced Directive 10/CT-TTg in 2026 that further promotes rooftop solar coupled with storage. To strengthen investor confidence, previously weakened by the legacy FiT problem, the EVN prosed a retroactive tariff cut of 43% for the affected projects (Reccessary 2026). However, a substantial gap still remains to meet the revised PDP8 target of 46–73 GW by 2030.
The progress of wind capacity development is also substantially falling behind the 2030 target. If Viet Nam maintains the annual growth rate of the onshore capacity around 13% and offshore 3% from the 2021–2025 period, it would achieve only around 10 GW onshore capacity and 1 GW offshore capacity by 2030, compared to its onshore and offshore targets of 26-38 GW and 6-17 GW by 2030, respectively. Measures have been undertaken to address challenges, including allowing investment and investor approval without competitive bidding and establishing a legal framework for offshore wind project development.
Renewable energy continues to receive strong backing. Offshore wind receives preferential policies and freedom for project and share transfers, while green hydrogen and green ammonia are explicitly supported. Nuclear energy is also reinstated under strict safety provisions.
A new category of emergency projects, fast-tracked to address shortages or disasters, will benefit from expedited approvals and exemptions, though these measures may compromise environmental safeguards.
Contractual and market reforms form another pillar. Detailed rules for Power Purchase Agreements (PPAs) and Power Service Supply Agreements (PSLAs) are set, with English allowed in foreign-invested projects(ho 2025).
Key uncertainties remain, as many critical provisions, including those for offshore wind, pricing, and contracts, await secondary regulations. Emergency project rules could also weaken transparency. Moreover, the dual push for fossil fuels and renewables risks tension with climate goals.
Solar
Solar PV deployment in Viet Nam has experienced rapid growth, particularly between 2019 and 2021. At the end of 2021, the installed solar capacity was 16.7 GW, including 7.6 GW of rooftop solar (Ember, 2023). Since then solar PV capacity has increased gradually, reaching 19.3 GW by 2025 (Ember, 2026). Between 2021 and 2024, solar installations slowed due to several factors.
Regulatory uncertainty, particularly changes to the rooftop solar feed-in tariff (FiT) scheme and restrictions on selling excess electricity to the grid, has discouraged investment (LTN & Partners 2024). Additionally, grid capacity limitations and curtailment issues have made it difficult to integrate growing solar generation (Intelligence 2025). Financial difficulties faced by the state-owned utility EVN, including delays in payments and retroactive tariff adjustments, further undermined investor confidence, contributing to the slowdown (Reuters 2025a).
The 2023 PDP8 foresaw about 12 GW by 2030 and up to 189 GW by 2050. The 2025 amendment raises the ambition to maximum 73 GW in 2030 and up to nearly 300 GW in 2050, with a strong emphasis on rooftop deployment. Half of all homes and offices are expected to deploy solar for self-consumption by 2030. This expansion reflects both declining solar costs and the need to exploit Viet Nam’s excellent solar potential.
The Directive 10/CT-TTg sets 2026 targets for national electricity savings, peak-load reduction, rooftop solar uptake and lower system losses, while encouraging rooftop solar paired with energy storage system (Viet Nam Government News 2026d). This provides more policy support to further scale up solar deployment.
Viet Nam added more solar power capacity than all other ASEAN countries combined in 2020 (Ember 2022). Between 2019 and 2020 alone, Viet Nam's solar capacity increased by 11.7 GW (EVN 2021). This solar boom experienced in Viet Nam can be attributed to a well-designed policy mix, which includes generous feed-in-tariffs and the exemption of renewable energy producers from income tax, import tariffs, and land lease payments. Viet Nam accomplished its 2025 solar targets as early as 2020 (Ember 2022). The average investment cost and levelised cost of energy for solar in Viet Nam are the lowest among the ASEAN countries, at respectively USD 690 per KW and USD 0.046 per kWh (IRENA 2022).
However, the FiT policy that once drove the solar boom is now facing a crisis of confidence. More than 170 solar and wind projects, representing an estimated USD 13 billion in investment, are at risk due to regulatory uncertainty surrounding the country’s feed-in tariff scheme (Guarascio and Guarascio 2025). To strengthen investor confidence, the EVN prosed a retroactive tariff cut of 43% for the affected projects (Reccessary 2026).
Hydro
Hydro power is the largest source of renewable energy in Viet Nam, representing 31% of the electricity generation mix in 2025 (Ember, 2026). The riverscapes of Viet Nam are among the most exploited in the world (Sasges and Ziegler 2023).
The 2025 PDP8 maintains Viet Nam's commitment to harnessing the full potential of its hydro resources. With most viable domestic potential already exploited, capacity is expected to stabilise at 33–35 GW by 2030 and rise to up to 40 GW by 2050, with only minor additions from small and pumped storage projects. According to the National Climate Change Strategy, Viet Nam will pursue the development of small hydro plants that adhere to environmental protection standards, while also expanding medium and large-scale hydroelectric projects (Viet Nam Government 2022c). Overall, hydropower’s role is increasingly one of grid balancing rather than major new supply.
Climate change risks disrupt water flows, intensify seasons, and heighten evaporation, directly impacting Viet Nam's hydroelectric production. The 2023 droughts caused the water levels in multiple reservoirs around the country to drop below the levels required for turbine operations (Asia News Network 2023). National projections show that El Nino is highly likely to end the rainy season earlier, lower rainfall and water supplies, thereby increasing the risk of drought, water shortages and saltwater intrusion during the 2026-27 dry season (Tuoi tre news 2026).
Wind
Wind plays a small but growing role in the power sector, accounting for about 4% of total generation in 2025, up from near-zero in 2020 (Ember, 2026). The installed onshore and offshore capacity respectively reached 5.135 MW and 1.104 MW at the end of 2025 (IRENA 2026).The 2025 PDP8 plan expected about 26–38 GW of onshore wind by 2030, and 84-91 GW by 2050, and 6-17 GW of offshore wind by 2030 and then 113–139 GW by 2050. If Viet Nam maintains the annual growth rate of the onshore capacity around 13% and offshore 3% from 2021–2025 period, it would achieve only around 10 GW onshore capacity and 1 GW offshore capacity by 2030, greatly falling short of its 2030 target.
Resolution 70 names offshore wind as a strategic priority. Since adopting the revised PDP8 in 2025, Viet Nam has taken steps to address regulatory barriers that had stalled offshore wind development. Resolution 253/2025/QH15 introduced special mechanisms to accelerate the offshore wind capacity development, including allowing investment and investor approval without competitive bidding, while Decree 272/2026/NĐ-CP recently established the legal framework for offshore wind projects development (Viet Nam Government News 2026b), providing enabling environment for offshore wind development. Resolution 20-NQ/TW subsequently reinforced this direction, targeting the development of 6–10 GW of offshore-wind projects by 2030 (thuvienphapluat.vn 2026c).
Nuclear
Viet Nam’s nuclear power ambitions have undergone a significant transformation over the past decade. Initially, the country pursued an ambitious nuclear development programme, with plans for 14 reactors by 2030. But in 2016, the National Assembly suspended all nuclear plans due to safety and economic concerns (Naidu 2018). This stance has shifted markedly in recent years, and in 2025, the government revived nuclear energy as a strategic priority in its revised PDP8. For the first time since the suspension, nuclear power was formally included in the electricity mix by reviving the unfinished projects which were at the advance stage of planning in 2016.
The 2023 PDP8 excluded nuclear entirely, consistent with Viet Nam’s 2016 decision to cancel the Ninh Thuan project. The amendment, however, revives nuclear with 4–6.4 GW planned for 2030–2035, rising to 10.5–14 GW by 2050. The government argued that the increased dependency on nuclear is the result of growing concerns about grid stability, particularly after recent grid failures due to the sudden rise in solar.
Even optimistic government estimates suggest that the earliest operational date for Ninh Thuan 1 would be 2035, with realistic expectations pushing it into 2037 or later (theinvestor.vn 2025). Financing remains a major hurdle: nuclear projects are capital-intensive, and earlier cancellations were due to escalating costs.
Viet Nam must also build a robust regulatory framework, ensure strong safety oversight, and develop the necessary human capital to operate and maintain nuclear plants. Public acceptance, land use issues, and environmental considerations add further complexity (NUCNET 2025).
Despite these challenges, Viet Nam signed an agreement with Russia in March 2026 to support the construction of Ninh Thuận 1, which would comprise two units with expected capacity of around 2,400 MW (Ministry of Industry and Trade 2026). The Government also approved a Strategy for the development and application of atomic energy for peaceful purposes through 2035, with a vision to 2050 (Government News 2026). This strategy targets completion of Ninh Thuận 1 and Ninh Thuận 2 by 2035, deployment of at least one small modular reactor project by 2035, and a nuclear power share of 6–8% of national electricity output by 2050 (Government News 2026).
Although nuclear electricity generation does not emit CO2, the CAT doesn’t see nuclear as the solution to the climate crisis due to its risks such as nuclear accidents and proliferation, high and increasing costs compared to alternatives such as renewables, long construction times, incompatibility with flexible supply of electricity from wind and solar and its vulnerability to heat waves.
Grid and storage
Although the policies implemented have been successful in driving investment in Viet Nam’s renewable energy sector, the lack of planning in transmission and distribution resulted in a severe grid failure (GREENCIC 2023). Viet Nam's solar PVs boom has led the National Load Dispatch Centre to announce a pause in new renewable capacity deployments in 2022 (IUCN 2022).
The solar deployment has been concentrated in the centre and south of the country, with solar energy comprising over 60% of installed capacity in some regions (IUCN 2022). The lack of accurate production forecasts contributes to the challenges experienced by the grid (VNEEC 2023). Prioritising the fast-tracking of approvals and investments in upgrading the power grid’s transmission and distribution infrastructure, as well as fostering interconnectivity among regions are key to utilize the potential of renewables (World Bank 2023).
While the 2022 moratorium paused new grid-connected solar/wind projects to allow time for grid upgrades, as of the plan revisions, the government has laid out clearer conditions and capacity targets for new projects. There is no evidence the pause remains fully in force; rather, new deployment is expected to align with upgraded grid readiness under PDP8.
The revised PDP8 gives high priority to expanding and strengthening the grid: adding 500 kV and 220 kV transmission lines, new high-voltage substations, and even HVDC converter stations. This is meant to relieve bottlenecks that previously held up new solar/wind deployment.
The focus is not only on physical infrastructure, but also operational improvements: regulatory reforms, better forecasting, system flexibility, and investment in energy storage (especially Battery Energy Storage Systems) to help with frequency stability and handling variable renewables (MoIT n.d.).
Even with PDP8, implementation lags remain. Grid investment has historically been behind generation growth which has led to curtailment and infrastructure overload in some regions.
In December 2025, Viet Nam adopted Resolution 253/2025/QH15 to address persistent bottlenecks in power planning, grid investment, offshore wind, direct power purchase agreements and strategic energy infrastructure during 2026–2030 (Viet Nam Government 2026e). While this is an improvement, it also provides special mechanisms for nationally important oil, gas and coal projects, creating risk for long-term carbon lock-in (Viet Nam Government 2026e).
Industry
Industrial process emissions mainly stem from cement production, followed by steel and ammonia production (Viet Nam Government 2019). This sector is projected to be the second largest in terms of emissions by 2030 based on the current policy pathway. It is also set to be the sector with the biggest health impact (EREA & DEA 2021). Viet Nam’s first NDC excluded industrial process emissions, but its 2020 and 2022 NDC updates included it (Viet Nam Government 2022e).
Policy attention to the entire industry sector has historically been low. In 2015, the Ministry of Industry and Trade approved the Green Growth Action Plan 2015–2020 for the industry sector, and the Ministry of Construction has an action plan until 2020 to reduce cement industry GHG emissions. The two plans together aim to reduce emissions by 20 MtCO2e by 2020 and 164 MtCO2e by 2030 compared to BAU levels.
In parallel, the Viet Nam National Energy Efficiency Program 3 (2019–2030) set intensity reduction targets for industrial subsectors, such as cutting chemical industry energy use by at least 10% and reducing the energy required to produce one tonne of cement from 87 kgOE in 2015 to 81 kgOE by 2030 (MoIT 2019). By 2025, all new industrial parks are also required to apply energy efficiency and conservation measures.
Since 2022, more substantial developments have emerged. Viet Nam is introducing an emissions trading scheme (ETS), beginning with the allocation of emission quotas to large facilities in the power, cement, and steel sectors—together responsible for nearly 40% of national emissions (Saigon Times 2025). Pilot quotas for 2025–2026 are being allocated now, with the scheme to be expanded in phases through 2030 (Vn Economy 2025a). Facilities are required to complete greenhouse gas inventories as a basis for quota allocation, marking a significant step in building a domestic carbon market.
In 2026, the government approved the first allowance allocations for 2025–2026, covering thermal power, steel and cement; established registry, trading, custody and settlement rules; and created a framework for international carbon-credit transfers under Article 6 (LuatVietnam 2026; Viet Nam Government 2026g, 2026a).
These measures improve the institutional credibility of Viet Nam’s carbon-pricing architecture. However, the pilot phase is unlikely to deliver strong near-term mitigation unless allowance allocation becomes more stringent. Decision 263/QĐ-TTg sets Viet Nam’s total pilot GHG emission quota at 243.08 MtCO2e in 2025 and 268.39 MtCO2e in 2026, an increase of around 10.4%, suggesting that the pilot aims to build market and compliance readiness rather than impose an immediate emissions reduction obligation (International Climate Initiative (IKI) 2026; Viet Nam Government 2026f).
A key foundation for Viet Nam’s industrial decarbonisation effort has been the gradual introduction of mandatory greenhouse gas inventories and reporting requirements. Under Decision 01/2022 and its subsequent updates, large facilities across energy-intensive industries—including cement, steel, and ceramics—are required to establish comprehensive emissions inventories (CIC 2024). These obligations are not only administrative: they underpin the allocation of emission quotas under the emerging domestic carbon market (S&P Global 2024).
International pressures, particularly the EU’s Carbon Border Adjustment Mechanism, are also accelerating Viet Nam’s regulatory reforms (S&P Global 2024). To respond, the government is combining emission quotas with sector-specific roadmaps. In 2024, a preliminary Industrial Decarbonisation Roadmap was published under the UNIDO-led Industrial Decarbonization Accelerator, outlining pathways for heavy industry transformation (UNIDO 2024).
Transport
In July 2022, Viet Nam adopted a roadmap for the transition to green energy in the transport sector, prioritising electrification and use of biofuels with expansion of E5 blending, targeting 100% of clean transportation by 2050 (Viet Nam Government 2022b). Since then, Viet Nam has moved beyond setting broad goals in the transport sector (such as universal electrification of buses, taxis, etc.) to developing more detailed policy instruments, roadmaps, and implementation plans.
In 2026, Viet Nam has operationalised its long-delayed E10 biofuel blending roadmap under Circular 50/2025/TT-BCT (Viet Nam Government 2026c). It requires nationwide use of E10 gasoline from 1 June 2026, while E5RON92 remains available until the end of 2030 (Viet Nam Government 2026c). However, this biofuel blending does not completely phase out fossil fuels. The use of biomass also raises concerns about increasing pressure on the agricultural and land-use sector, and imposing negative impact on health and environment due to air pollution.
The adoption of the Action Plan to Accelerate Energy Transition by the Ministry of Transport is a central step, giving specificity to what needs to occur through 2030 and beyond (e.g. infrastructure, fleet replacement, modal shifts toward rail/sea/inland navigation) (NDC Transport Initiative for Asia 2024).
In the urban transport sector, this roadmap sets goals: for all new buses to be using electricity or green energy by 2025, all new taxis to be electric vehicle by 2030, and for 100% of buses and taxis to either be electrified or to be using green energy by 2050. This roadmap also includes interim targets for the electrification of railways and shipping. Battery electric vehicles are already exempt from registration fees from three years starting March 2022 (Le, Posada, and Yang 2022).
Alongside with the implementation of the 2022 green transport roadmap, fiscal incentives for battery electric vehicles, rapid domestic EV market growth, and new 2026 measures to expand charging infrastructure in apartment buildings and urban areas has rapidly scaled up EV adoption in Viet Nam (LuatVietnam 2022; VietnamPlus 2026).
Vietnam has the largest electric vehicle (EV) market in south-east Asia (IEA 2026c). As Viet Nam’s main domestic electric-vehicle manufacturer and a key private-sector actor in the country’s transport electrification strategy, VinFast delivered about 170,000 units of domestic EVs, nearly twice the volume of the previous year (Reuters 2026a).
Viet Nam remains one of the most motorcycle-dependent countries in the world, and two-wheelers continue to dominate its transport landscape. As of July 2026, there are in total 84 million motorcycles registered, accounting for 90% of all motorised vehicles in the country (baodientuvtv 2026). Motorcycle ownership has become nearly universal: close to nine in ten households own at least one, and in major cities such as Hanoi and Ho Chi Minh City, two-wheelers account for over 70–80% of travel demand.
Within this context, electric two and three-wheelers have emerged as an important, if still modest, component of the national fleet. In 2025, Viet Nam was the world’s third-largest market for electric two (E2W) and three-wheelers after China and India, with new sales reaching around 0.74 million units and total stock around 2.4 million in the same year (IEA 2026b). The E2W market was valued at around USD 222 million in 2024, with projections suggesting it could nearly triple by 2033 (IMARC 2025). Although new sales of E2W steadily increasing at more than 10% per year, E2Ws still represent only 3% of the overall two-wheeler stock (IMARC 2025).
EV deployment is also increasingly linked to city-level air-quality policy, including low-emission zones and restrictions on fossil-fuel vehicles in Hà Nội.(Viet Nam Government 2026d) While these developments are promising, the main challenge for further decarbonisation lies in scaling up charging infrastructure buildout.
To reduce energy use of this sector for the long-term, public transport expansion and modal shift are also necessary. The National Strategy for Climate Change to 2050 includes measures for restructuring the transport market, including the transition from road transport to inland waterway and coastal transport; make the transition from road to railway, increase railway goods transport percentage; increase transport efficiency via building and expanding road network (Viet Nam Government 2022b).
Buildings
Energy demand in the buildings sector has risen in the past decade as result of Viet Nam’s successful implementation of universal electrification and the increase in use of electrical home appliances (APEC 2022). During 2012-2022, the total energy demand increased by nearly 20%, while total combustion CO2 emissions decreased by 28%, highlighting energy efficiency of electrification (APERC 2025). As a consequence, the use of biomass has seen a significant drop.
The government has introduced some energy efficiency policies, including the VNEEP3 (MOIT, 2019). An official Prime Minister Decision (No.04/2017/QD-TTg) in 2017 sets out mandatory energy labelling and minimum energy efficiency standards roadmap for equipment and appliances (MoIT 2019). The list and roadmap for equipment subject to energy labelling has been updated and supplemented by newer energy-efficiency and labelling regulations Circular 52/2025/TT-BCT from 2026 (thuvienphapluat.vn 2026f). In the National Green Growth Strategy there are specific tasks relating to the development of green buildings, and energy efficiency of buildings (Viet Nam Government 2019).
A major milestone was the amendment of the Law on Energy Efficiency and Conservation, which took effect in 2026 (VNEEP 2025b). This reform strengthened state oversight of energy efficiency, broadened the scope of mandatory energy labelling and minimum performance standards to include not only appliances but also construction materials, and created clearer mechanisms for energy audits, monitoring, and workforce training (VNEEP 2025a). It also introduced financial tools to support investment in efficiency improvements, signalling the government’s recognition that upfront cost remains a barrier for developers and households alike.
Meanwhile, VNEEP3 has continued to guide sectoral efforts, with explicit targets for reducing energy consumption in buildings. The results are becoming visible, as by 2024, Viet Nam had recorded over 550 green-certified buildings covering more than 13 million square metres of floor area, a number that already surpasses targets initially set for 2025 and 2030 (B-Company 2025a; Vn Economy 2025b).
Agriculture
In 2024, agriculture represented 15% of Viet Nam’s GHG emissions with methane from rice cultivation and livestock production as dominant sources (Gütschow, Busch, and Pflüger 2025).
In 2022, the government issued the Methane Emissions Reduction Action Plan to 2030 (Decision 942) (Viet Nam Government 2022d). This was the first comprehensive plan to directly address methane, setting quantified limits for both cultivation and animal husbandry emissions. As per the Methane Emissions Reduction Action Plan, the objective is to limit methane emissions from agriculture, setting goals to limit cultivation emissions to 30.7 (42.2) MtCO2e and animal husbandry emissions to 15.2 (16.8) MtCO2e by 2030 (2025), aligned with Global Methane Pledge.
The National Strategy for Climate Change to 2050 also adopted in 2022, reinforced these targets, requiring the agricultural sector to cut emissions by 43% from its projected 2030 baseline, limiting total emissions to around 64 MtCO2e (Gütschow et al., 2022a). The strategy framed this not only as a mitigation task but also as a development opportunity: restructuring the sector, promoting organic and circular agriculture, and deploying climate-smart practices that improve resilience while lowering emissions.
Since 2023, the Ministry of Agriculture and Rural Development has begun to translate these commitments into more concrete programmes. A major milestone was the design of a Low-Emission Crop Production Plan (Ministry of Agriculture and Environment 2025). This plan targets at least a 30% reduction in methane emissions from crop cultivation by 2030, and a 10% reduction in overall agricultural GHG emissions compared to 2020 levels.
The plan aims to apply low-emission farming practices across 2.5 million hectares, focusing on commodity production zones where mitigation potential is greatest. To underpin this, the Ministry has launched the High-Quality, Low-Emission Rice Production Protocol and the Measurement, Reporting, and Verification (MRV) Protocol for high-quality, low-emission rice cultivation (Ministry of Agriculture and Environment 2025).
Parallel to this, the government launched the flagship “One Million Hectares of High-Quality, Low-Emission Rice” programme in the Mekong Delta, Viet Nam’s most important rice-growing region and a global hotspot for methane emissions from paddy cultivation (IRRI 2024). The programme, designed to run to 2030, has already achieved significant outcomes, including nearly doubling its initial 2024–2025 growth area target, improving utilisation efficiency of seed, fertiliser, irrigation water and pesticides, and reducing emissions by 3-4 tonnes of CO2-e per hectare per season (International Rice Research Institute 2026).
Forestry
Viet Nam’s land use, land use change and forestry sector is currently a net sink and is intended to play a large role in meeting Viet Nam’s updated NDC. Under the government reported business-as-usual scenario (BAU), the LULUCF sector is estimated to be a sink of 49 MtCO2e in 2030 (Viet Nam Government, 2022a).
In its 2050 National Climate Change Strategy, Viet Nam has set a target for the land use and forestry sector to reduce 70% of emissions and increase 20% of carbon absorption and achieve a total sink capacity of 95 MtCO2e by 2030. Viet Nam’s forest coverage currently stands at just over 42%, equivalent to nearly 13.9 million hectares that meet national forest standards (News 2023). This is close to, but still below, the government’s target of maintaining 43% forest cover set out in the National Climate Change Strategy (Viet Nam Government 2022c).
The government is also seeking to improve forest quality and ensure sustainable management, recognizing that degraded or young forests provide far less carbon sequestration than mature, healthy ecosystems.
The 2017 Law on Forestry remains the backbone of forest governance, but new regulations have been introduced (MNRE, 2019). Most notably, Decree 27/2024/ND-CP, effective from March 2024, amended earlier forestry decrees to regulate the temporary use of forest land for infrastructure projects such as electricity networks (Viet Nam Government 2024).
The decree sets conditions to minimise damage, requires restoration after use, and aims to balance development pressures with the need to maintain forest cover. At the same time, the Government continues to maintain forest protection and restoration as part of its climate strategies (e.g. via REDD+-related programs, forest monitoring, improving forest quality). In March 2026, the Green Climate Fund has approved around USD 72 million payment for REDD+ results-based projects, expected to have avoided 56.8 million tonnes of CO2-e (Green Climate Fund 2026). Some emphasis is being placed on digital tools: for example, digital forest monitoring, timber traceability, law enforcement aided by technology (B-Company 2024).
In May 2026, Decree 180/2026/ND-CP established Viet Nam’s national legal framework for forest carbon sequestration and storage services, which regulates forest carbon projects, MRV requirements, credits granting rules, and domestic and international transaction procedures (Viet Nam Government News 2026c). The decree links forest carbon to Viet Nam’s emerging domestic carbon market and Article 6 framework. While it would be important to increase the global reforestation and afforestation area, its carbon credits scheme, once linked to the international market under the Article 6 framework, may incentivise other countries to buy “cost-effective” international credits rather than invest in decarbonising the whole economy.
Waste
In 2024, the waste sector represented 5% of Viet Nam’s GHG emissions excluding LULUCF (Gütschow et al. 2025). In 2018, the Prime Minister approved the National Strategy for General Management of Solid Waste to 2025 with a 2050 vision, which included energy recovery and GHG reduction measures (MNRE, 2019).
According to the 2050 National Climate Change Strategy, the emissions reduction from the waste sector would be 61% by 2030 and 91% by 2050. This is supported by policy plans such as implementing solutions for managing and reducing waste from production to consumption, expand responsibilities of manufacturers; and an increased reuse and recycling of waste.
One of the most important milestones came in early 2025 with the approval of the National Action Plan for Implementing the Circular Economy until 2035 (Decision No. 222/QĐ-TTg) (B-Company 2025b). This plan sets out a long-term vision to reduce waste, improve recycling and reuse, and increase resource efficiency across sectors such as agriculture, manufacturing, construction, tourism, and services. It also calls for stronger institutional frameworks, clearer technical standards, and improved mechanisms for data sharing and monitoring (Viet Nam Circular Economy 2025).
The Law on Environmental Protection (effective 2022) created the legal basis for waste sorting and extended producer responsibility (EPR) (Law No. 72/2020/QH14 on Environmental Protection – Policies 2024). Recent updates to EPR regulations, most notably Decree 05/2025/ND-CP, broaden the scope of products covered and create more flexibility for recycling pathways (B-Company 2025b). Decree 110/2026/NĐ-CP operationalises the Viet Nam’s EPR framework by detailing producer and importer responsibilities (to be fulfilled through either recycling practices or financial contribution that supports recycling activities), compulsory recycling ratio, reporting requirements, contribution payment procedure (Viet Nam Government 2026b). While primarily a waste and circular-economy regulation, it can support emissions reductions through improved recycling, reduced material demand and better waste management.
Viet Nam will also adopt advanced solutions in treating wastes and wastewater to reduce methane emissions (Viet Nam Government 2022a). The Methane Emissions Reduction Action Plan includes the goal of cutting methane emissions from solid waste management and wastewater treatment by 13% at 22 MtCO2e by 2025, and by 30% at 17.5 MtCO2e by 2030, compared to an implied 2020 baseline level of 25.3 MtCO2e (Viet Nam Government 2022d).
The 2023 PDP8 promotes power generation through organic and solid waste combustion, with estimated potentials of 7 GW and 1.8 GW. In the 2025 update, although there is no specific mention of organic or solid waste, the plan aims for more than 2 GW waste to energy by 2030 and 5 GW by 2050, marginally lower than 2023 version of the PDP8. In 2026, Hanoi launched a USD 200 mwaste-to-energy project, which is expected to process 2000 tonnes of waste per day and generate 45MW of electricity for the national grid (Vietnam+ (VietnamPlus) 2026).
Further analysis
Latest publications

Stay informed
Subscribe to our newsletter